Available 7 Days/Week       MON - FRI  8am - 7pm       SAT - SUN  10am – 6pm
Call us (386) 456-6380
Apply Now

Tag: #lehighacresmortgage

Florida waterfronts and skyline

?? Florida’s iconic waterfronts meet smart investing with DSCR mortgages.

Start your home purchase qualifier with no personal info and discover how DSCR loans focus on property income, not personal income. Whether you’re eyeing a condotel or a traditional investment property, DSCR programs simplify qualification with no lease requirements and support loans up to $5 million.

You can finance multiple properties, including non-warrantable condos, while enjoying predictable terms and a clear path to grow your real estate portfolio.

Boost your investment game with a program designed for Florida’s unique market.

Get your rate today and see how DSCR can help with your next purchase.

? Link in profile

#DSCRMortgage #FloridaInvesting #RealEstateFinance #CondotelLoans #InvestmentProperty

Why Buyers Shouldn’t Overlook a Fall Move

Why Buyers Shouldn't Overlook a Fall Move Simplifying The Market

You’ve been waiting for something to change before you buy. It just might not be the thing you expected…

While everyone’s paying attention to mortgage rates, only the savviest buyers know that the changing season can start tipping things in their favor. 

Because every fall, buyers tend to get more to choose from, better prices, and more room to negotiate. And that’s why Hannah Jones, Senior Economist at Realtor.com, says:

We always see that the best time to buy window usually falls in the early fall around October.

And that’s exactly why, if you’ve been waiting for a better moment to buy, this season may be worth a closer look – even with rates where they are.

1. There Are More Homes To Choose From

One of the biggest frustrations buyers have had over the past few years has been a lack of choices. Fall tends to help with that.

Based on seasonal trends, Realtor.com data shows there are typically more homes available for sale in September through November than during any other season of the year (see graph below):
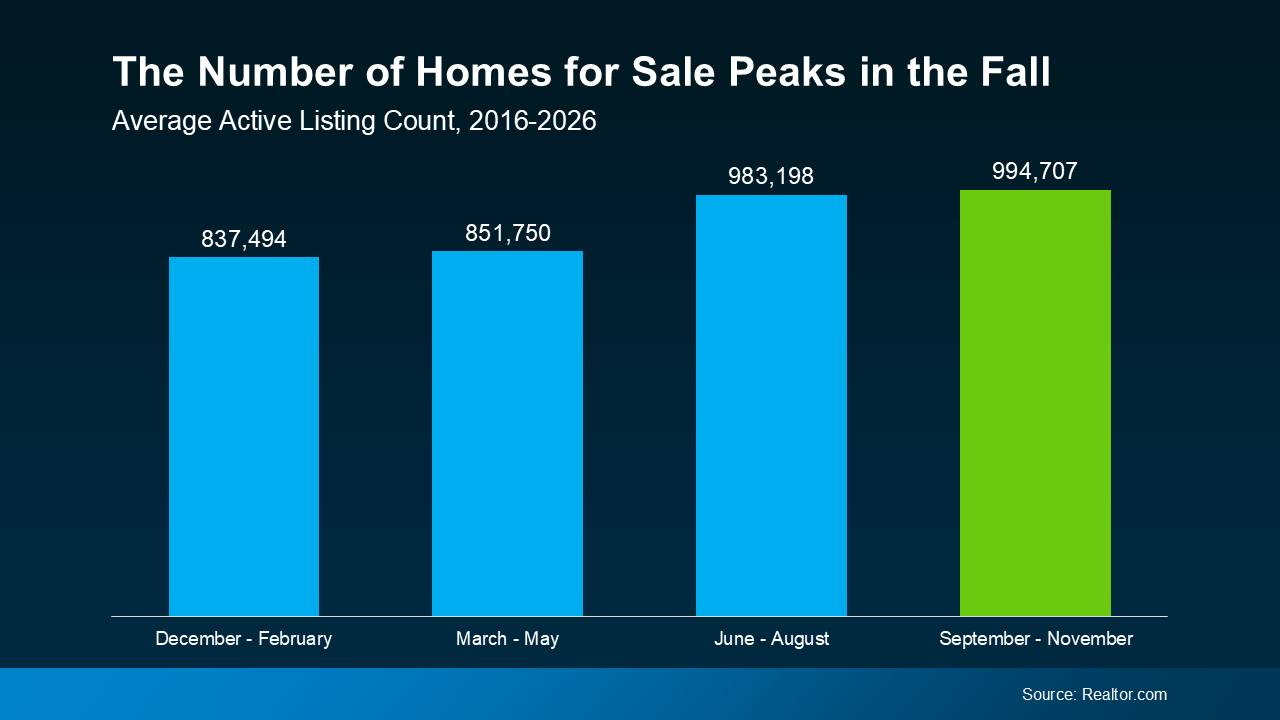
a graph of a number of homesWhy does this happen? Homes that hit the market in spring and summer don’t all close right away. Some sit. New listings keep coming. And inventory builds as the year goes on.

By fall, you’re looking at the largest pool of available homes all year. That makes it easier to find one that works for your needs and your budget. And if anything, this should be more true this year. Rates that are higher for longer tend to help inventory grow even more.

More choices can mean fewer compromises. You’re more likely to find the right home, not just the one that happens to be available.

2. Asking Prices Start To Drop

Having more choices is great. But if every home is still priced too high, that only gets you so far. That’s where fall’s second advantage kicks in: asking prices start their seasonal decline. 

HousingWire data shows this trend over time (see graph below):
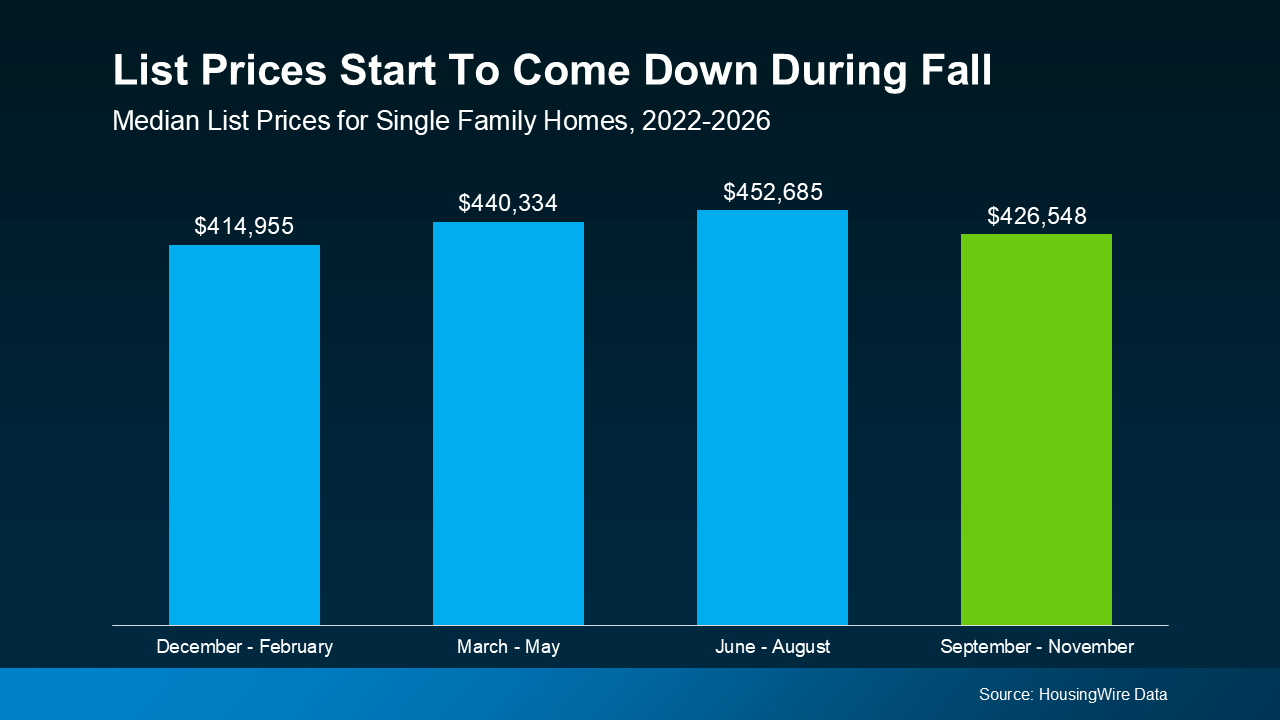
a graph of a number of blue and green barsIt works like this. Spring and early summer are when sellers feel the most confident because that’s when demand is typically strongest. So, many homeowners price their homes higher during those periods because of the uptick in demand.

But every year, like clockwork, that dynamic starts to change by fall. Buyer activity slows down as the weather cools off. So, sellers have to price a bit lower to try to draw buyers in. And that’s good for your bottom line.

3. More Sellers Are Willing To Negotiate

But fall doesn’t just bring more choices and lower asking prices. It also brings more sellers who are increasingly motivated to get a deal done. 

You can see it in the data. Most years, fall is when price cuts peak according to Realtor.com data (see graph below):
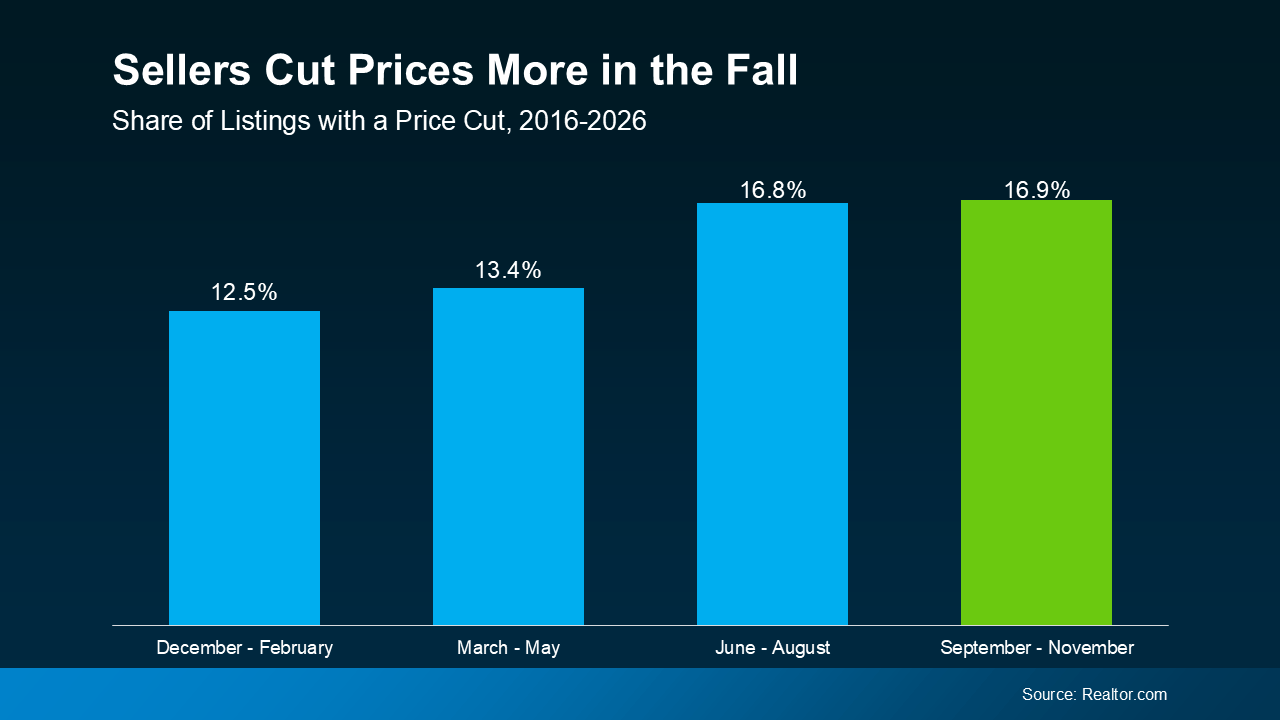
a graph of sales with numbers and text

While it’s not a big difference from summer, this fall you’ll have more negotiation power than you’d have if you wait until the first half of 2027. Here’s why. 

If a home is on the market in the fall, many sellers are eager to get it sold before the holidays. And since there are usually fewer buyers active in the fall, that often leads to another opportunity to snag a better deal. As the National Association of Realtors (NAR) explains:

“Less competition can lead to better deals. While homes are not selling as fast as during the summer, sellers may be more willing to negotiate.”

Even a small seller compromise here can make a meaningful difference for you. 

As an example, a 5% price drop on a $500,000 home is $25,000. That could mean you end up borrowing less, keeping more money in savings, having room in the budget for updates after you move in, or simply making the monthly payment feel more manageable.

Bottom Line

Of course, every market moves a little differently. But here’s what doesn’t change: Fall consistently buyers. More homes. Lower asking prices. Motivated sellers. 

If you’ve been waiting for your search to feel a little more doable, this season may be worth another look.

Have a quick conversation with a local agent about what’s happening in your market. That way you can find out whether this fall gives you opportunities you may not have had a few months ago.
Think New Homes Cost More? Not Right Now.

Think New Homes Cost More? Not Right Now. Simplifying The Market

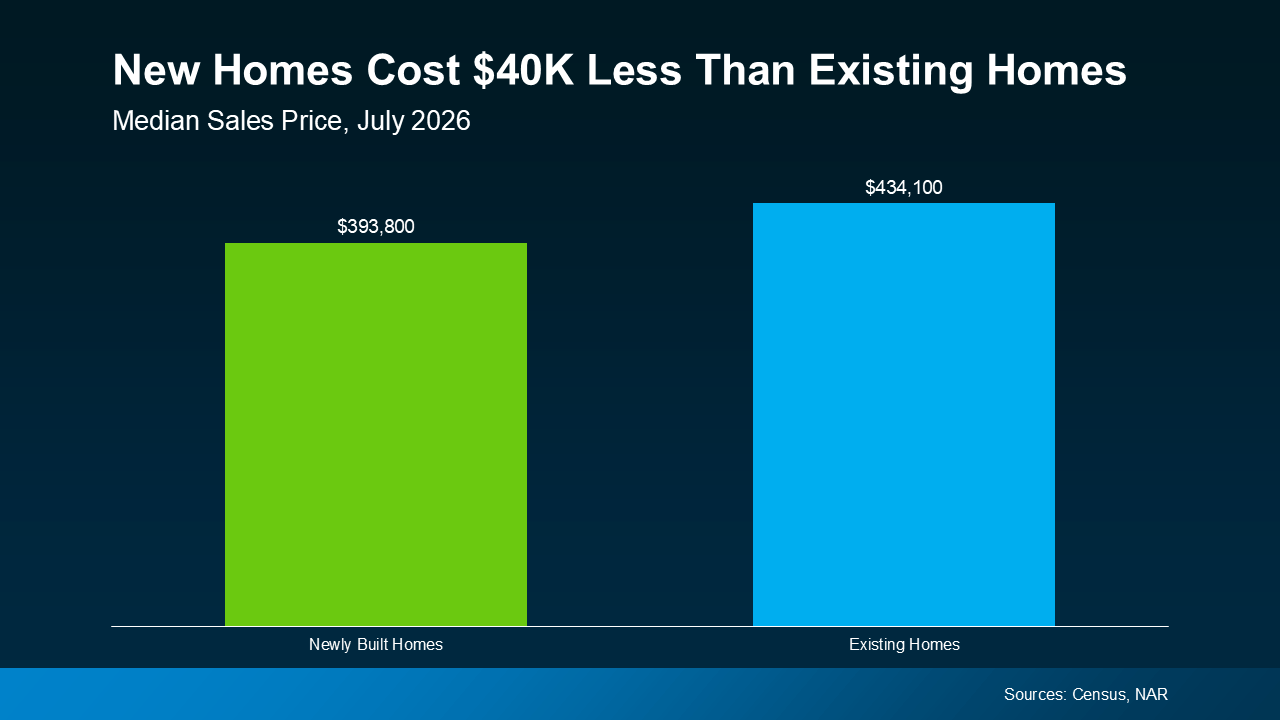
Most people think a newly built home costs more than an existing one. But right now, that’s actually backwards. Newly built homes are more affordable than existing ones in a lot of markets. And that’s because builders are cutting prices and stacking on incentives to try to keep their inventory moving.

Here’s why that’s really important for any would-be homebuyer to know.

Newly Built Homes Are the Better Deal Right Now

According to the latest data from the Census and the National Association of Realtors (NAR), a newly built home now typically costs about $40,000 less than an existing one (see graph below):

a graph of a house costBuilders aren’t like homeowners who can wait for the right offer. Unsold homes cost them money as long as they sit empty. So, builders cut prices and add incentives to keep them moving. That trend has carried into August. NAHB’s latest numbers:
  • 35% of builders cut prices, with an average reduction of 6%. 

  • 63% offered incentives like covering closing costs or buying down your mortgage rate. 

And those incentives can make a real dent in what you pay upfront and every month after. Plus, since everything is new and many builders offer warranties, you could save on home maintenance costs too. And with affordability where it is, every dollar counts.

So, don’t cross new builds off your list just yet. Yes, you may think they cost more, but that’s not always the case. 

If you can get brand-new everything for less than buying an existing home, isn’t that at least worth looking into? 

Don’t Let the Builder Pick Your Teammate

But before you tour a single model home, there’s one thing worth figuring out first – who’s actually working for you once you walk through that door.

That friendly rep in the builder’s sales office works for the builder, not you. Their job is to protect the builder’s bottom line, not yours. Your own agent flips that. 

They know the local market, so they can tell you if the builder’s price and upgrades stack up against other options nearby. They’ll negotiate on your behalf, whether that’s a lower price, free upgrades, or a rate buydown. 

A good agent will also push for a home inspection. Builders won’t always bring it up, but it’s a step you shouldn’t skip, even on a new build. And your agent will be in your corner, so you know what you’re buying and get the best deal possible. 

Bottom Line

New homes may actually cost less than an existing home right now. And that’s opening up a window for you to get brand-new for less.

If you want a list of new home communities near you that are currently offering incentives or doing price cuts, reach out to a local agent. When you have your own agent, you’ll have someone in your corner helping you get the best deal possible.  

Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.

Thinking About Tapping into Your 401(k) To Buy a Home? Read This First. Simplifying The Market

Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you’ve caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is. 

Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything.

Why Dipping into a 401(k) Can Be Tempting

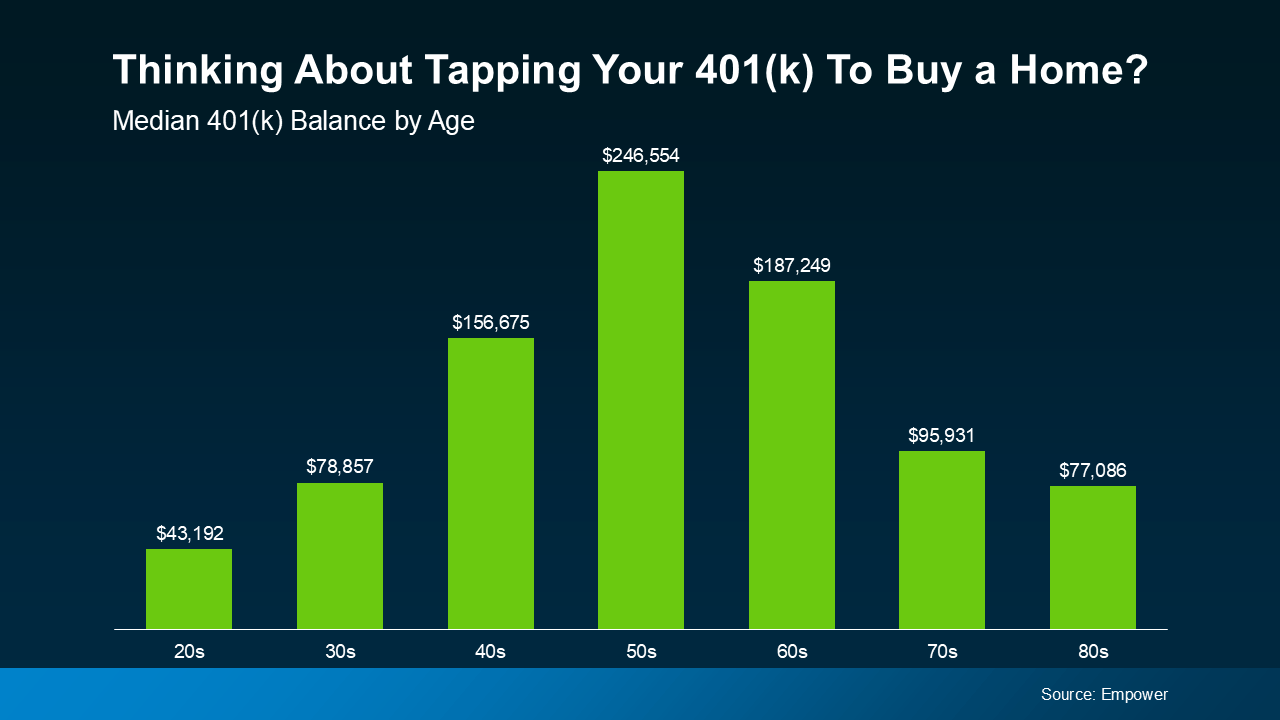
Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below):

a graph of green barsAnd when you’ve got a good chunk saved and your dream home is right there, reaching for it can feel like an easy call.
But dipping into your retirement savings to buy a home could cost you a penalty and set back your finances later on. That’s why it’s a good idea to explore other options for your down payment first. As Redfin says: 

If you’re struggling to save enough for a down payment, you may be wondering if tapping into your 401(k) is the right option. While it’s possible, doing so comes with significant risks, like early withdrawal penalties and lost investment growth.

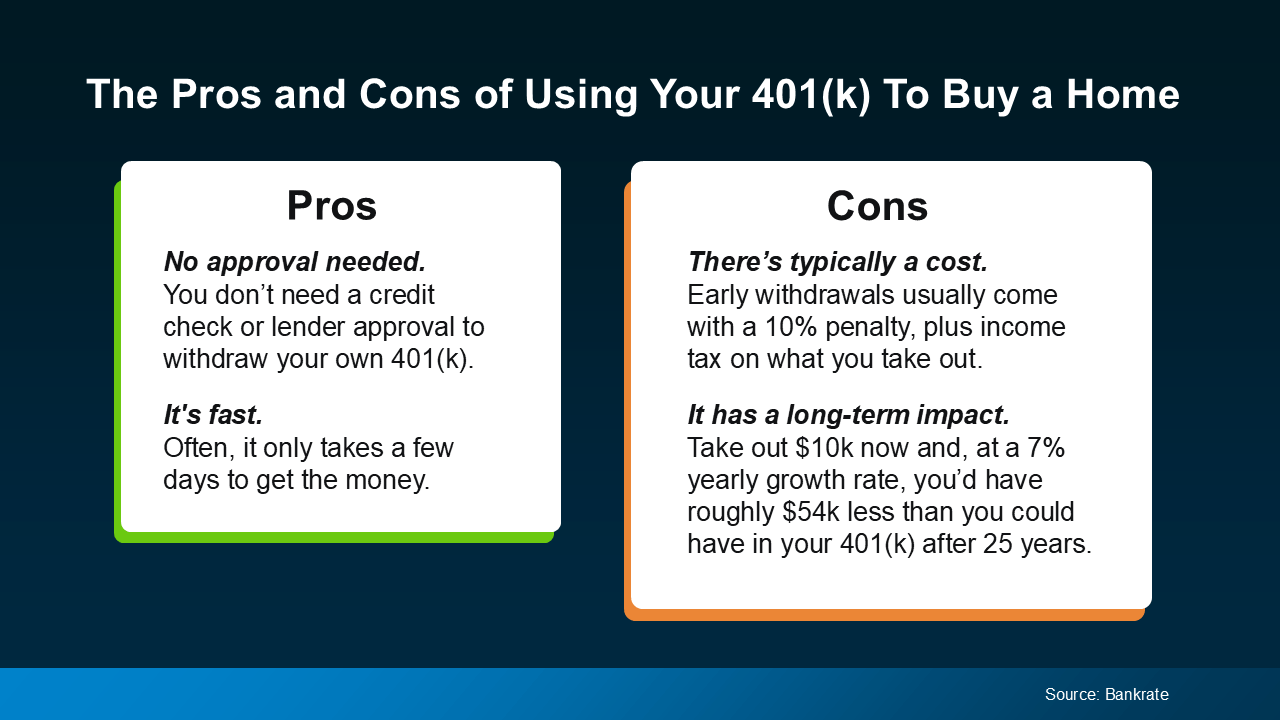
Before you decide, have a financial advisor help you compare the upsides to the risks. Bankrate points to a few of each (see visual):

a screenshot of a computer screen

Other Options Worth Exploring First

Your 401(k) isn’t the only way to finance a home purchase. Redfin outlines a few other options to look into before you decide what to do:

  • Low and No-Down Payment Loans: FHA loans, for example, allow qualified buyers to put down as little as 3.5% of the home’s price, depending on their credit scores.

  • Down Payment Assistance Programs: Many national and local programs can help reduce what you pay toward your down payment or closing costs.

Make a Plan Before You Make a Move

No matter which route you take, talk with a financial expert first. The buyers who come out ahead build a solid plan with the right professionals before starting their journey to homeownership. As NerdWallet puts it:

Even if you’re convinced a 401(k) loan is the way to go, it’s important to understand the risks at the outset.

Bottom Line

Affordability is definitely a challenge, but that doesn’t mean tapping your 401(k) is your only way in if you want to buy.

If you’re considering using your 401(k) savings for a down payment, weigh all your options and talk with a trusted financial advisor before you make any decisions. They’ll help you make a plan to fit your goals and your budget. 

Higher Rates Could Actually Help Housing Supply – Here’s How.

Higher Rates Could Actually Help Housing Supply – Here’s How. Simplifying The Market

You may have heard the number of homes for sale isn’t growing like it was. And maybe that has you worried you won’t find a home you love when it’s time to make your move.

But that may be about to change. Here’s why your pool of options may actually start ticking back up again.

Growth Has Slowed, But It Hasn’t Stopped

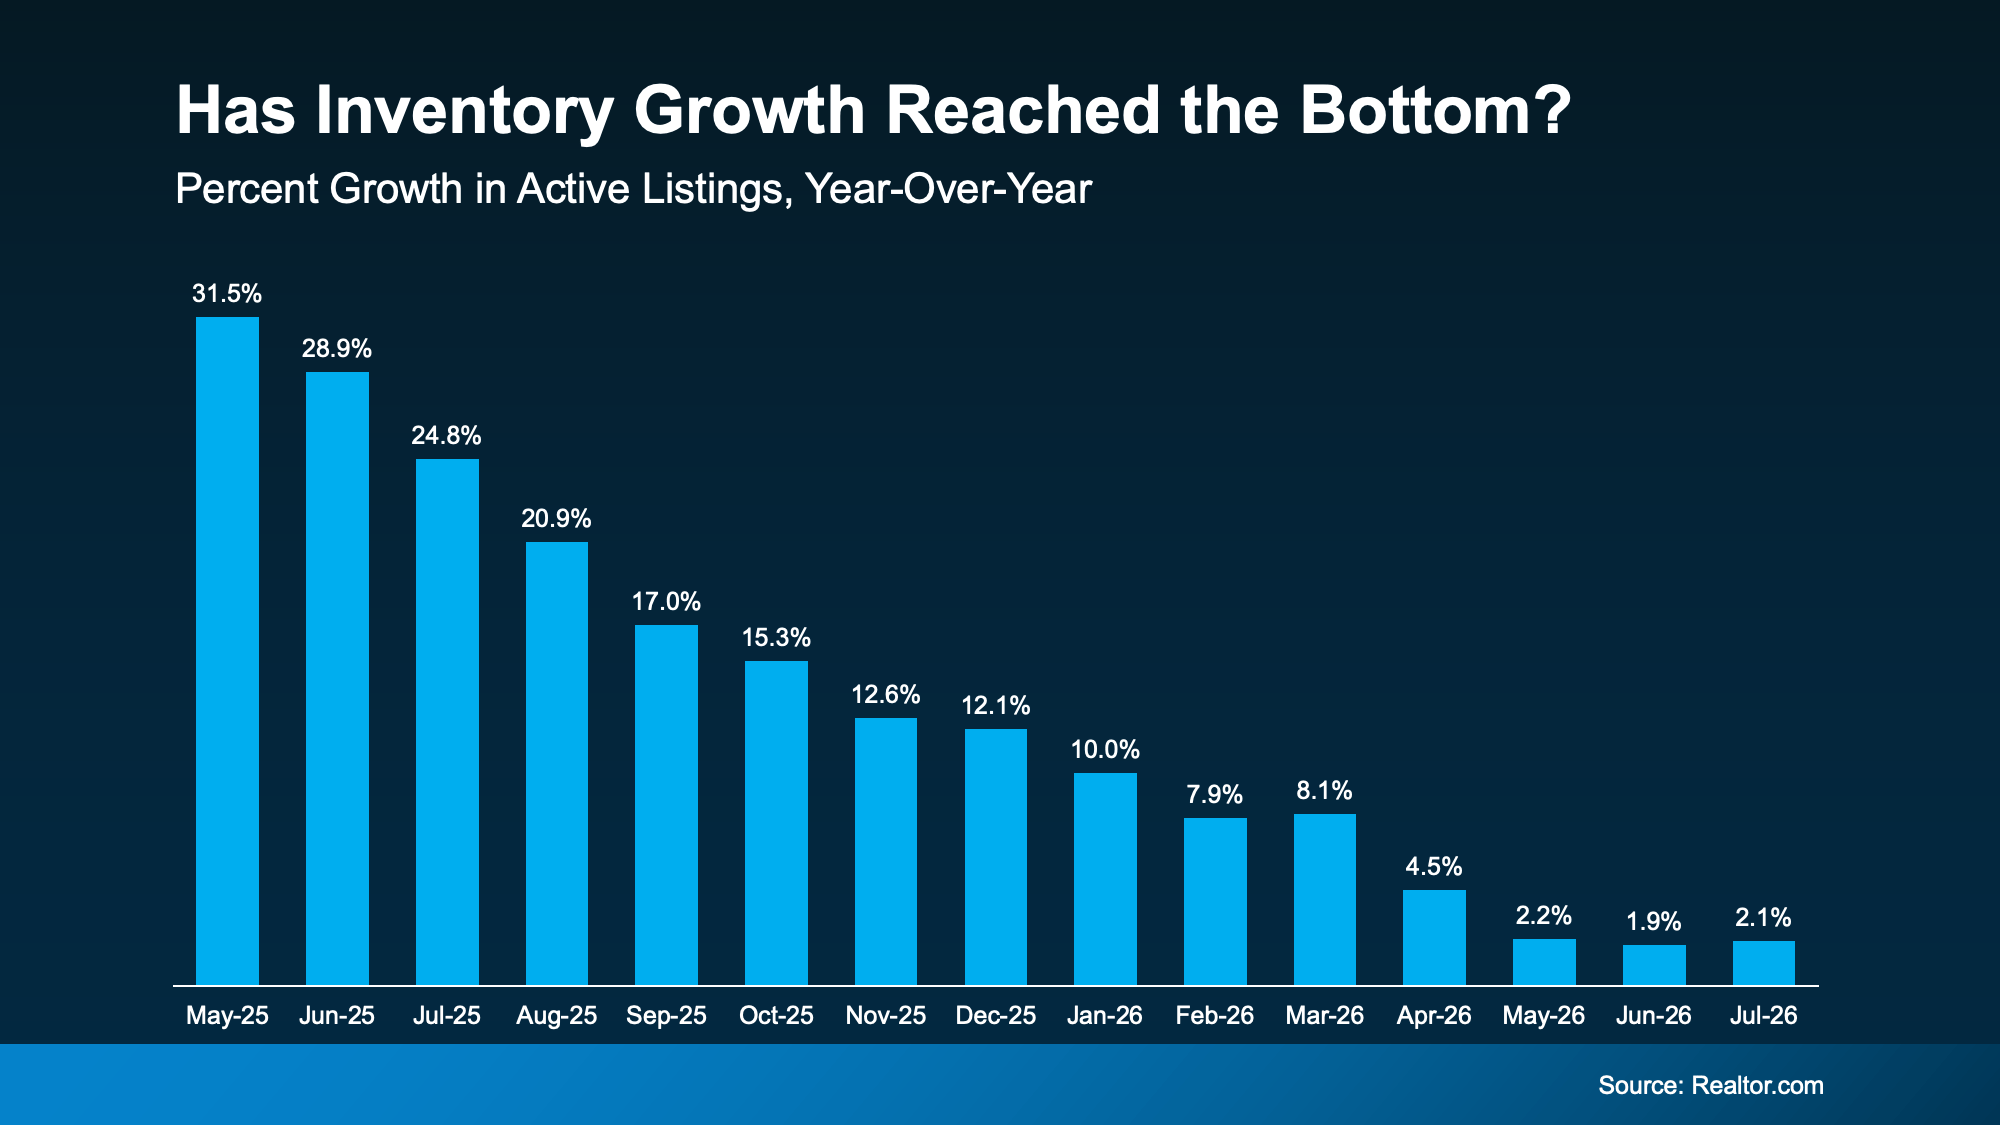
Active listings were up 2.1% year-over-year in July, according to Realtor.com. Back in January, inventory was up 10%. And in May of 2025, it was up 31.5%. So, growth has cooled off a lot over the last year.

The past 3 months, though, have all seen inventory growth land in roughly the same range, which is a sign this slowdown may be nearing its floor (see graph below):

a graph of growth in a blue background

So, what does that mean for you?

Homes are still coming onto the market. Every single one of these bars shows a period where inventory grew. So, don’t be discouraged or let this make you think you’re out of options. Plus, we’ve seen more stability in the numbers lately, which is a good sign.

The Most Homes for Sale Since 2019

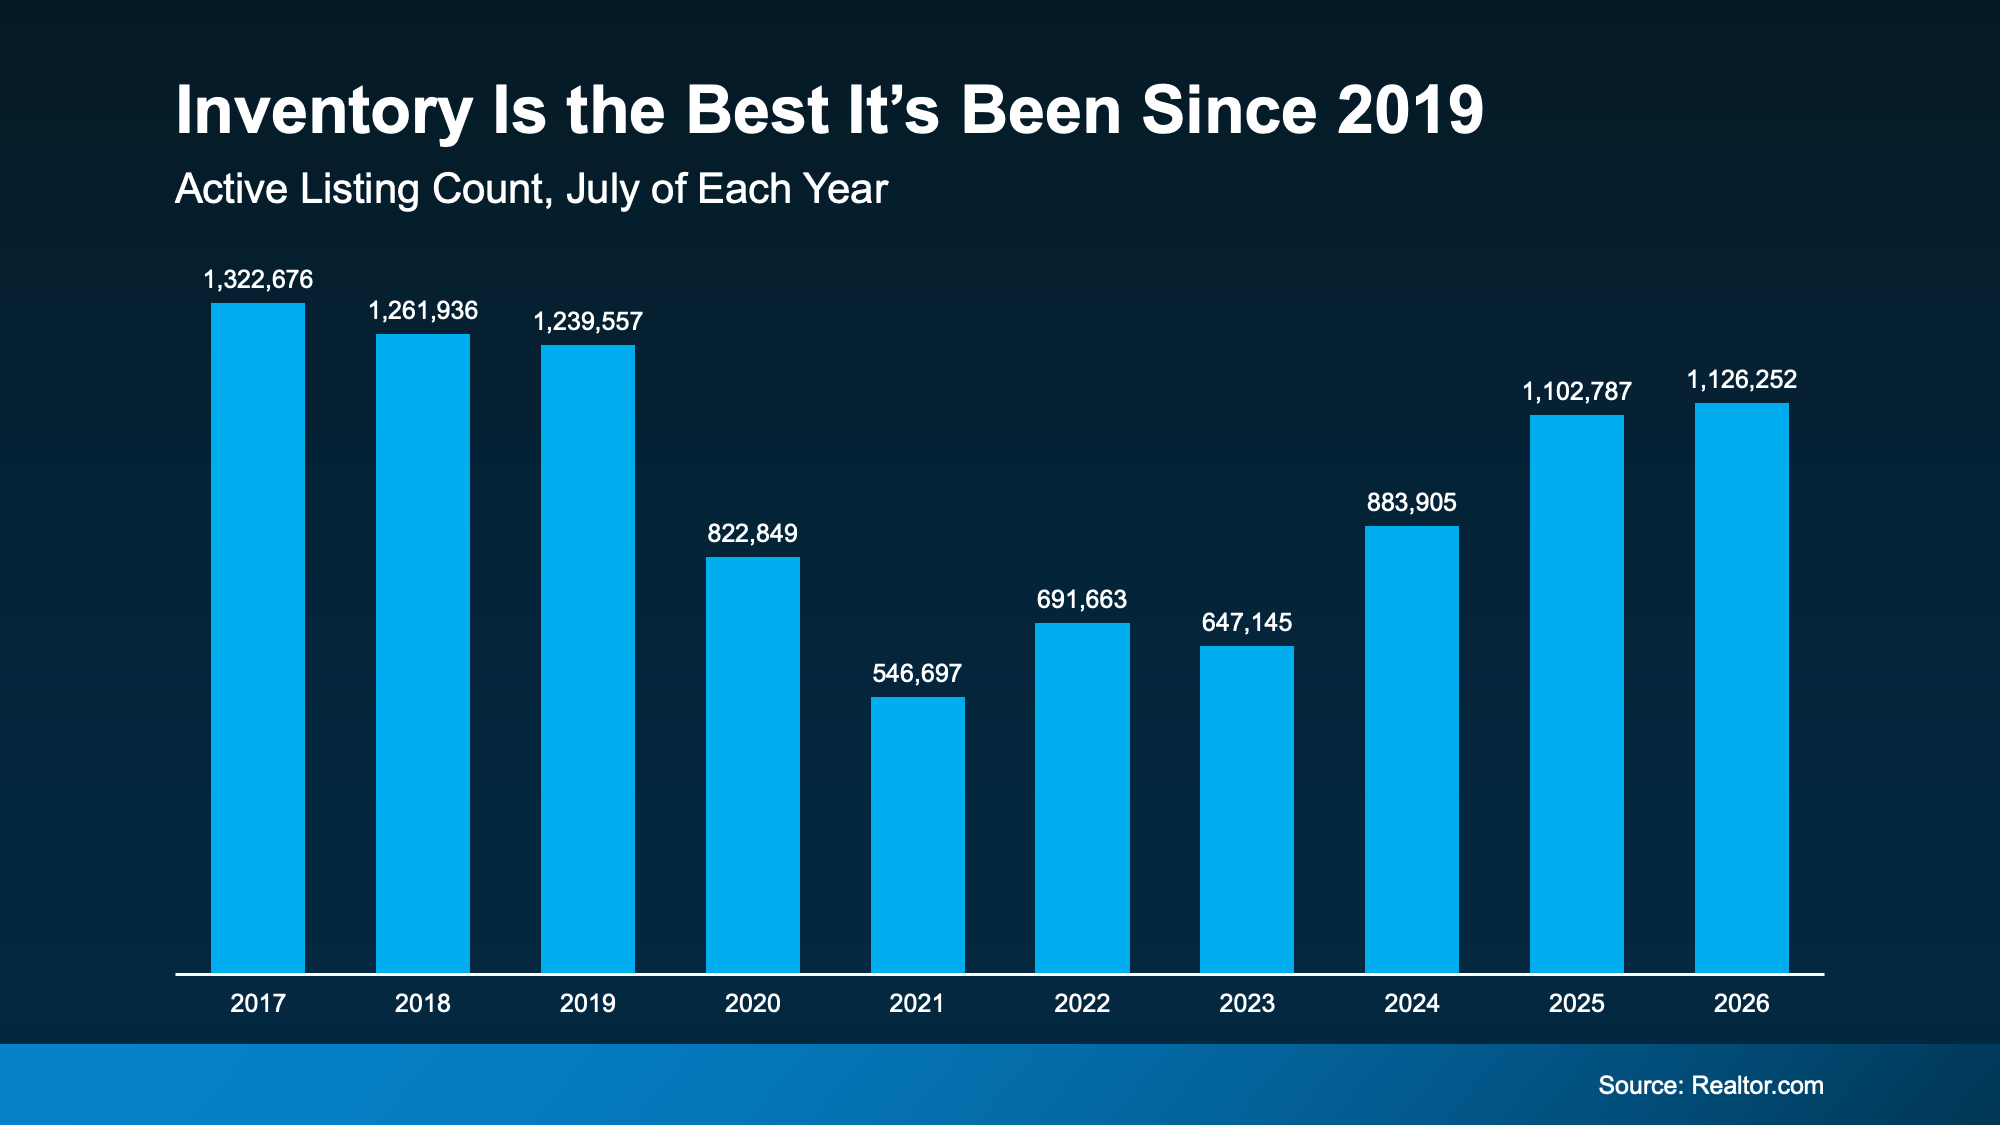
Compared to the rock-bottom lows of 2021, inventory has climbed back substantially. Nationally, the number of homes for sale has been up year-over-year consistently now for 33 months. And inventory has almost doubled in just a few years. So don’t get too hung up on the pace of that increase.

This July was actually the best July for inventory since 2019 (see graph below):

a graph of blue bars with white text

Now, the market still needs about 150k listings to get back to pre-pandemic levels, but things are quickly approaching normal. And experts think we may even be back to 2019 levels by the end of this year, even with the slowdown we’ve already seen.

And that’s thanks to one unlikely factor: mortgage rates

Why Higher Rates May Actually Help Inventory Grow

It works like this. When mortgage rates climb, inventory tends to climb with them. As Mike Simonsen, Chief Economist at Compass, explains:

When rates rise; inventory rises. When rates fall; inventory falls. So, from July last year to March this year, rates ease lower and all the inventory growth of the past several years evaporated. If rates move higher from here or stay elevated for [a] longer period of time, then we should expect supply to build again.

Well, rates are expected to hold in the mid-to-upper 6% range for a while longer, and Realtor.com‘s latest forecast has inventory ending 2026 up 3.6% year-over-year.

That means 2 things:

  • Inventory growth is forecast to pick up a little bit throughout the rest of the year.

  • And, inventory is projected to close the year at a historically normal level, right about where it stood at the end of 2019.

For buyers, that’s a win. Even if today’s rates aren’t your favorite, they’re helping the number of homes on the market to grow. And more homes for sale means more choices, more room to negotiate, and less pressure to rush your search.

Bottom Line

The number of homes for sale is growing slowly but surely, and that means more options for your move. Want to see what’s available in your area? Reach out to a local real estate agent.