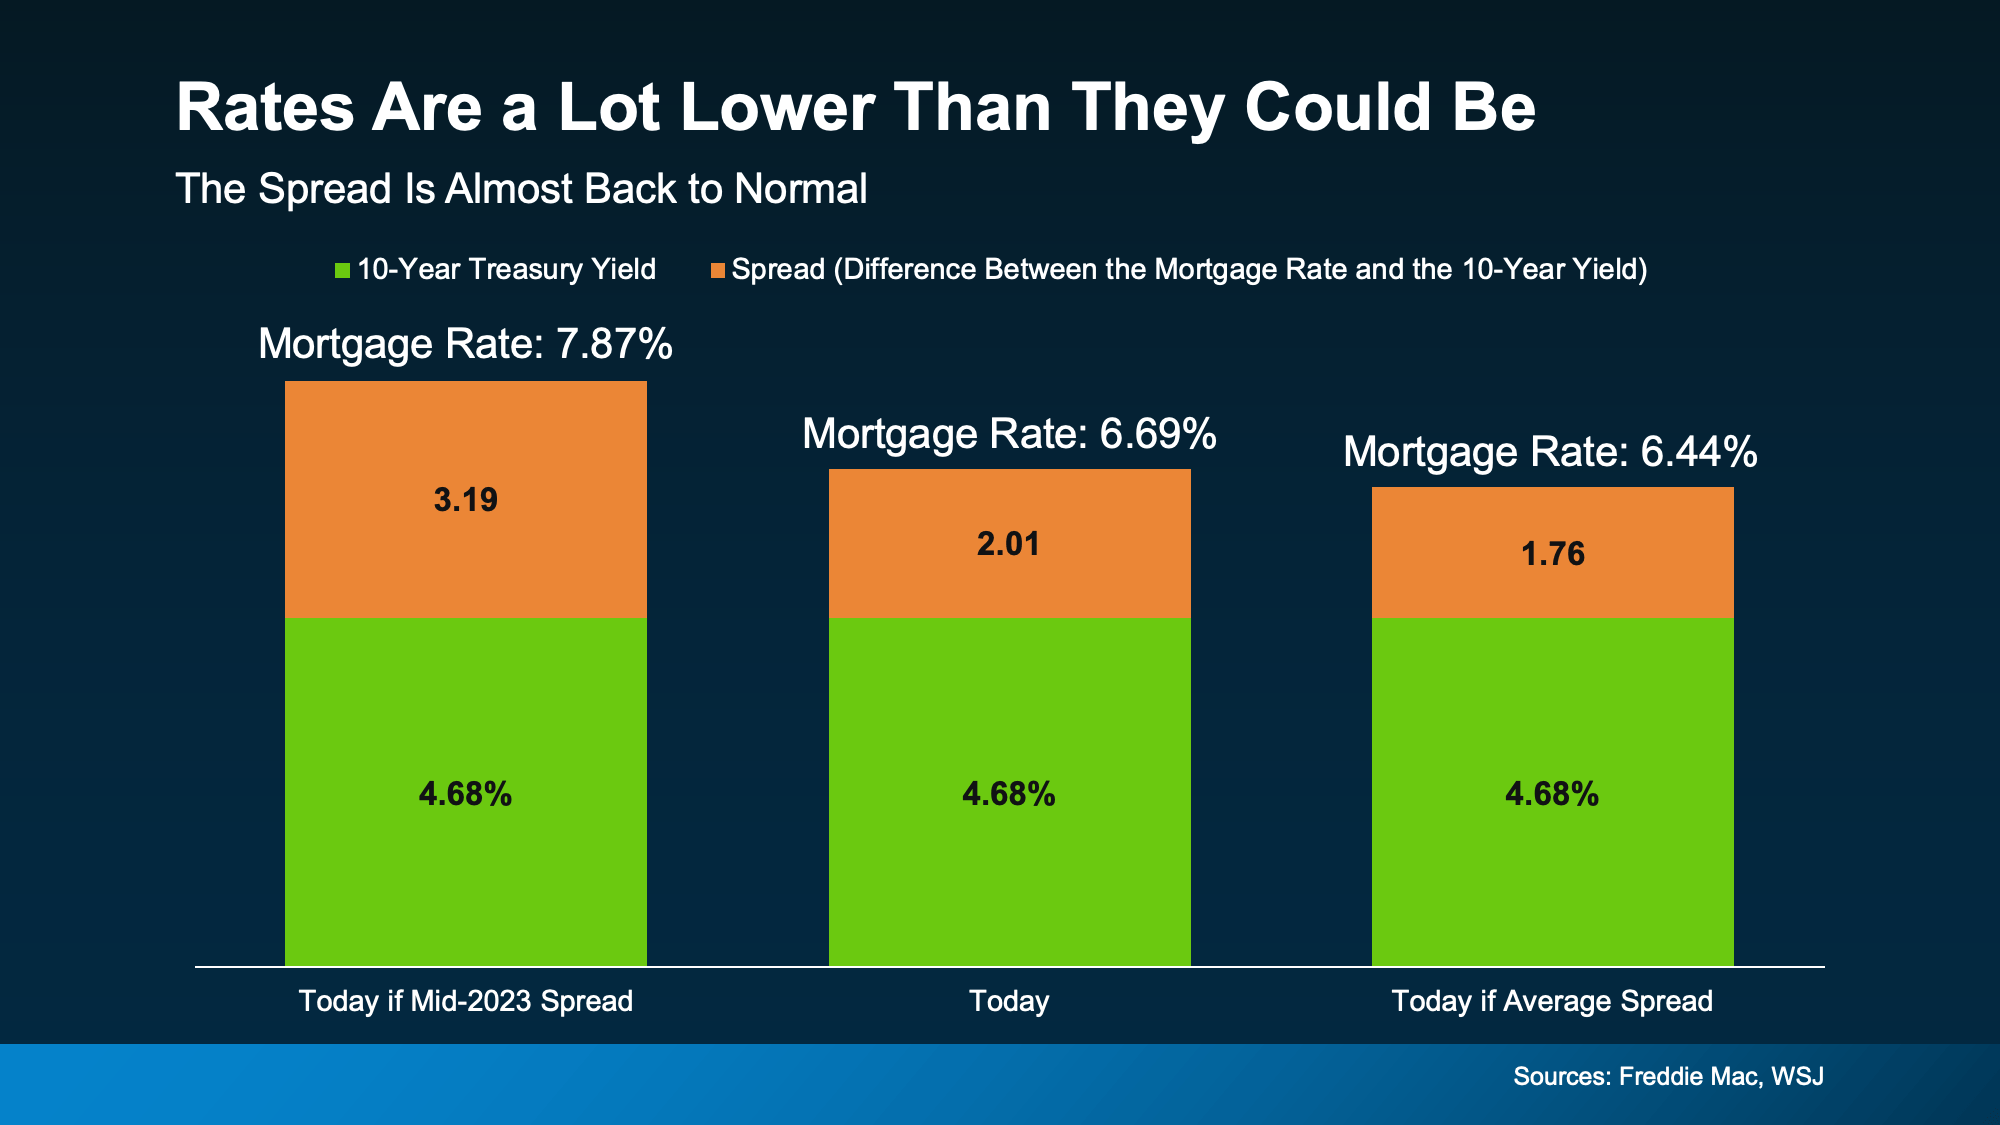Available 7 Days/Week       MON - FRI  8am - 7pm       SAT - SUN  10am – 6pm
Call us (386) 456-6380
Apply Now

Why Buyers Shouldn’t Overlook a Fall Move
Why Buyers Shouldn't Overlook a Fall Move Simplifying The Market

You’ve been waiting for something to change before you buy. It just might not be the thing you expected…

While everyone’s paying attention to mortgage rates, only the savviest buyers know that the changing season can start tipping things in their favor. 

Because every fall, buyers tend to get more to choose from, better prices, and more room to negotiate. And that’s why Hannah Jones, Senior Economist at Realtor.com, says:

We always see that the best time to buy window usually falls in the early fall around October.

And that’s exactly why, if you’ve been waiting for a better moment to buy, this season may be worth a closer look – even with rates where they are.

1. There Are More Homes To Choose From

One of the biggest frustrations buyers have had over the past few years has been a lack of choices. Fall tends to help with that.

Based on seasonal trends, Realtor.com data shows there are typically more homes available for sale in September through November than during any other season of the year (see graph below):
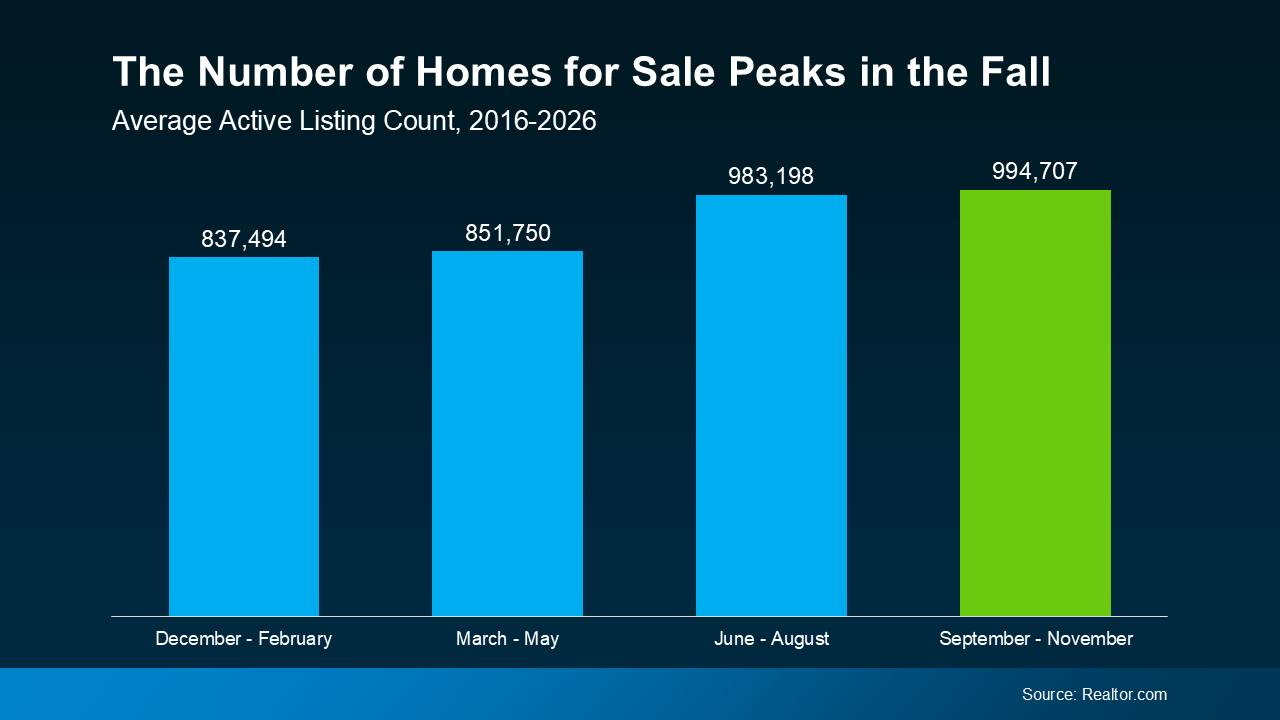
a graph of a number of homesWhy does this happen? Homes that hit the market in spring and summer don’t all close right away. Some sit. New listings keep coming. And inventory builds as the year goes on.

By fall, you’re looking at the largest pool of available homes all year. That makes it easier to find one that works for your needs and your budget. And if anything, this should be more true this year. Rates that are higher for longer tend to help inventory grow even more.

More choices can mean fewer compromises. You’re more likely to find the right home, not just the one that happens to be available.

2. Asking Prices Start To Drop

Having more choices is great. But if every home is still priced too high, that only gets you so far. That’s where fall’s second advantage kicks in: asking prices start their seasonal decline. 

HousingWire data shows this trend over time (see graph below):
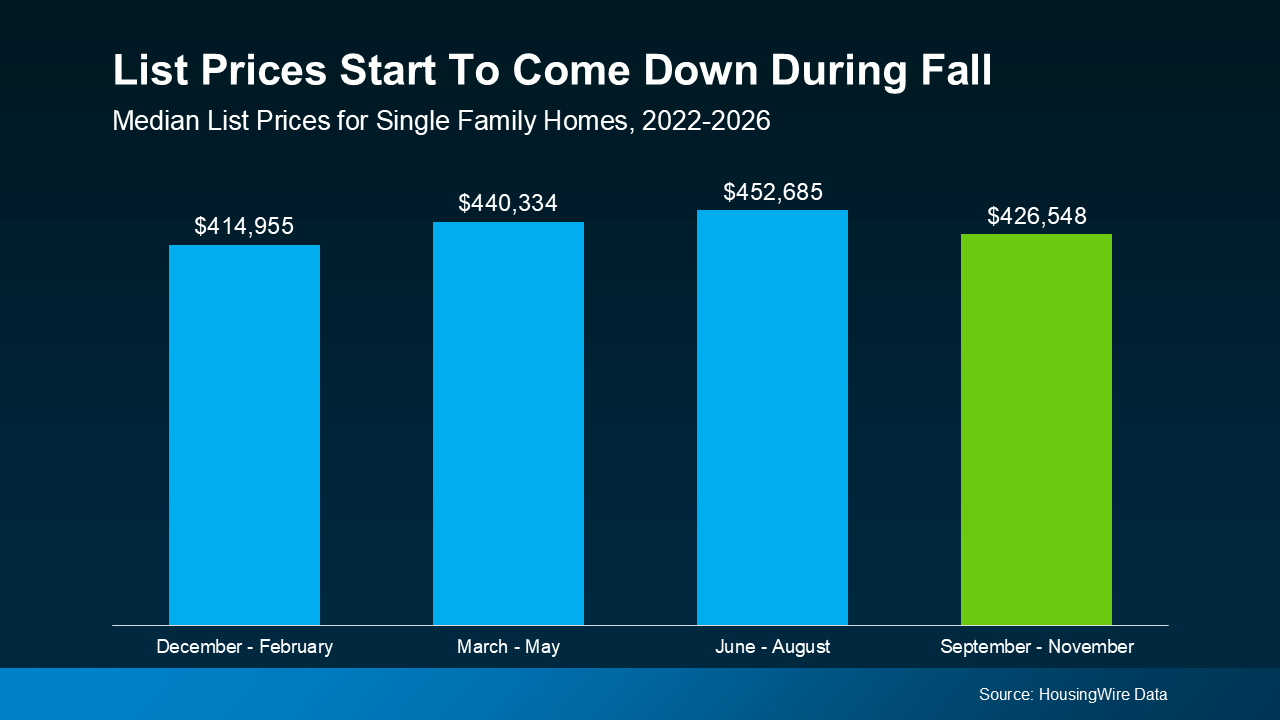
a graph of a number of blue and green barsIt works like this. Spring and early summer are when sellers feel the most confident because that’s when demand is typically strongest. So, many homeowners price their homes higher during those periods because of the uptick in demand.

But every year, like clockwork, that dynamic starts to change by fall. Buyer activity slows down as the weather cools off. So, sellers have to price a bit lower to try to draw buyers in. And that’s good for your bottom line.

3. More Sellers Are Willing To Negotiate

But fall doesn’t just bring more choices and lower asking prices. It also brings more sellers who are increasingly motivated to get a deal done. 

You can see it in the data. Most years, fall is when price cuts peak according to Realtor.com data (see graph below):
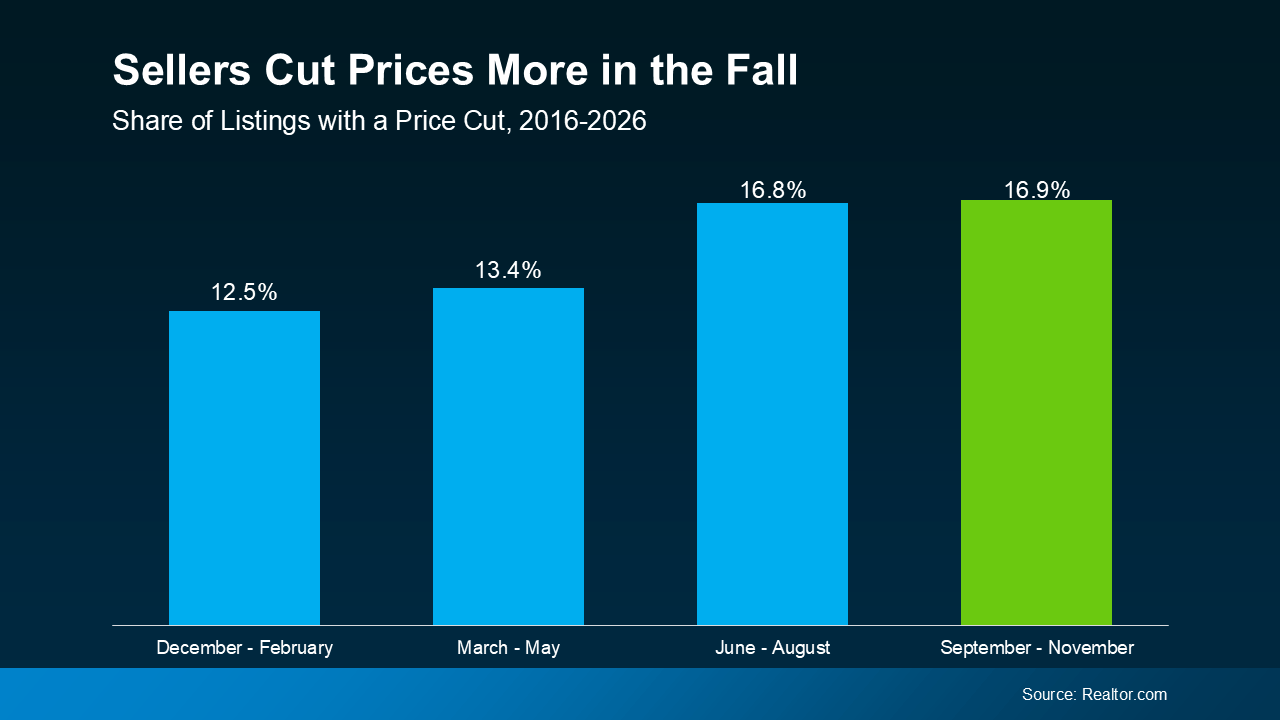
a graph of sales with numbers and text

While it’s not a big difference from summer, this fall you’ll have more negotiation power than you’d have if you wait until the first half of 2027. Here’s why. 

If a home is on the market in the fall, many sellers are eager to get it sold before the holidays. And since there are usually fewer buyers active in the fall, that often leads to another opportunity to snag a better deal. As the National Association of Realtors (NAR) explains:

“Less competition can lead to better deals. While homes are not selling as fast as during the summer, sellers may be more willing to negotiate.”

Even a small seller compromise here can make a meaningful difference for you. 

As an example, a 5% price drop on a $500,000 home is $25,000. That could mean you end up borrowing less, keeping more money in savings, having room in the budget for updates after you move in, or simply making the monthly payment feel more manageable.

Bottom Line

Of course, every market moves a little differently. But here’s what doesn’t change: Fall consistently buyers. More homes. Lower asking prices. Motivated sellers. 

If you’ve been waiting for your search to feel a little more doable, this season may be worth another look.

Have a quick conversation with a local agent about what’s happening in your market. That way you can find out whether this fall gives you opportunities you may not have had a few months ago.
Think New Homes Cost More? Not Right Now.

Think New Homes Cost More? Not Right Now. Simplifying The Market

Most people think a newly built home costs more than an existing one. But right now, that’s actually backwards. Newly built homes are more affordable than existing ones in a lot of markets. And that’s because builders are cutting prices and stacking on incentives to try to keep their inventory moving.

Here’s why that’s really important for any would-be homebuyer to know.

Newly Built Homes Are the Better Deal Right Now

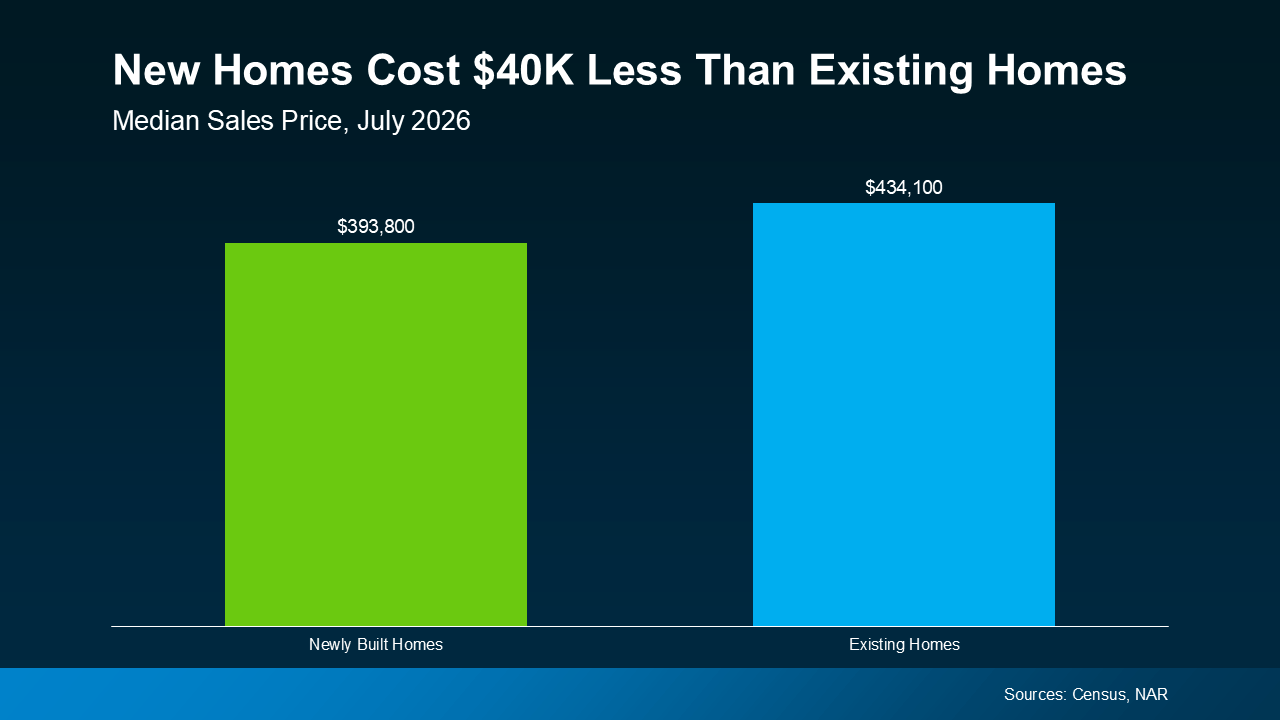
According to the latest data from the Census and the National Association of Realtors (NAR), a newly built home now typically costs about $40,000 less than an existing one (see graph below):

a graph of a house costBuilders aren’t like homeowners who can wait for the right offer. Unsold homes cost them money as long as they sit empty. So, builders cut prices and add incentives to keep them moving. That trend has carried into August. NAHB’s latest numbers:
  • 35% of builders cut prices, with an average reduction of 6%. 

  • 63% offered incentives like covering closing costs or buying down your mortgage rate. 

And those incentives can make a real dent in what you pay upfront and every month after. Plus, since everything is new and many builders offer warranties, you could save on home maintenance costs too. And with affordability where it is, every dollar counts.

So, don’t cross new builds off your list just yet. Yes, you may think they cost more, but that’s not always the case. 

If you can get brand-new everything for less than buying an existing home, isn’t that at least worth looking into? 

Don’t Let the Builder Pick Your Teammate

But before you tour a single model home, there’s one thing worth figuring out first – who’s actually working for you once you walk through that door.

That friendly rep in the builder’s sales office works for the builder, not you. Their job is to protect the builder’s bottom line, not yours. Your own agent flips that. 

They know the local market, so they can tell you if the builder’s price and upgrades stack up against other options nearby. They’ll negotiate on your behalf, whether that’s a lower price, free upgrades, or a rate buydown. 

A good agent will also push for a home inspection. Builders won’t always bring it up, but it’s a step you shouldn’t skip, even on a new build. And your agent will be in your corner, so you know what you’re buying and get the best deal possible. 

Bottom Line

New homes may actually cost less than an existing home right now. And that’s opening up a window for you to get brand-new for less.

If you want a list of new home communities near you that are currently offering incentives or doing price cuts, reach out to a local agent. When you have your own agent, you’ll have someone in your corner helping you get the best deal possible.  

Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.

Thinking About Tapping into Your 401(k) To Buy a Home? Read This First. Simplifying The Market

Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you’ve caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is. 

Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything.

Why Dipping into a 401(k) Can Be Tempting

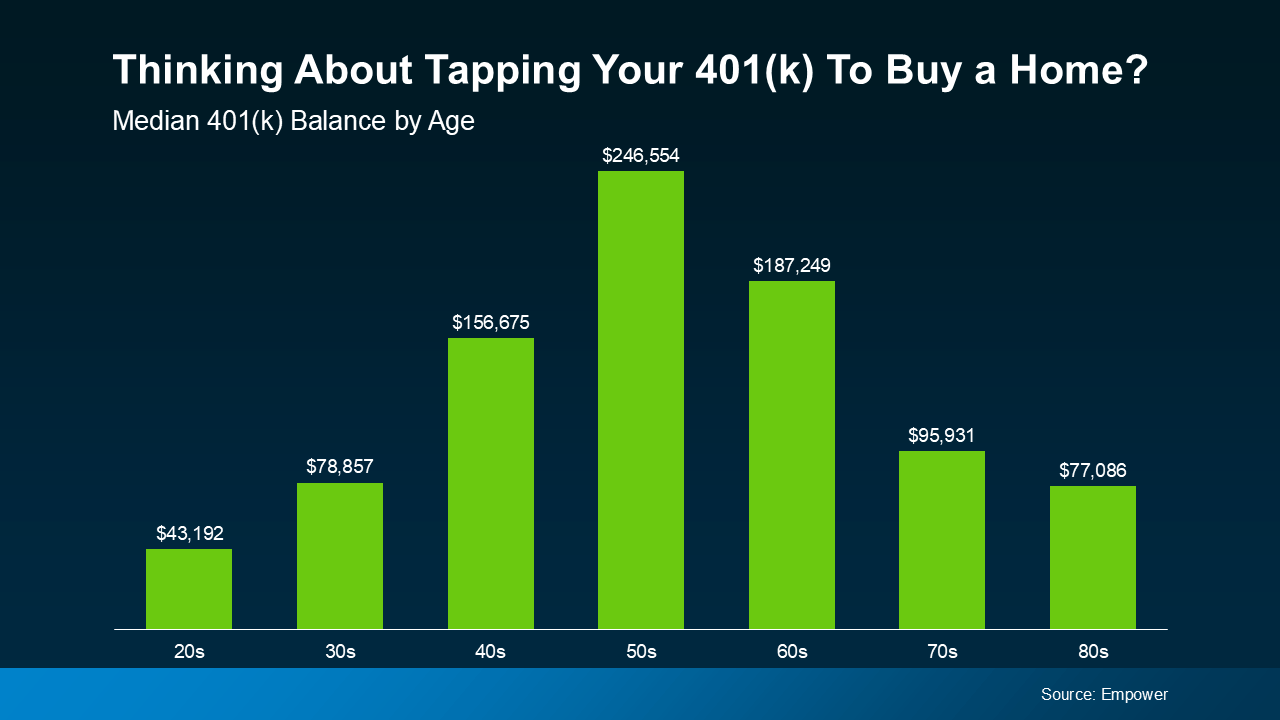
Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below):

a graph of green barsAnd when you’ve got a good chunk saved and your dream home is right there, reaching for it can feel like an easy call.
But dipping into your retirement savings to buy a home could cost you a penalty and set back your finances later on. That’s why it’s a good idea to explore other options for your down payment first. As Redfin says: 

If you’re struggling to save enough for a down payment, you may be wondering if tapping into your 401(k) is the right option. While it’s possible, doing so comes with significant risks, like early withdrawal penalties and lost investment growth.

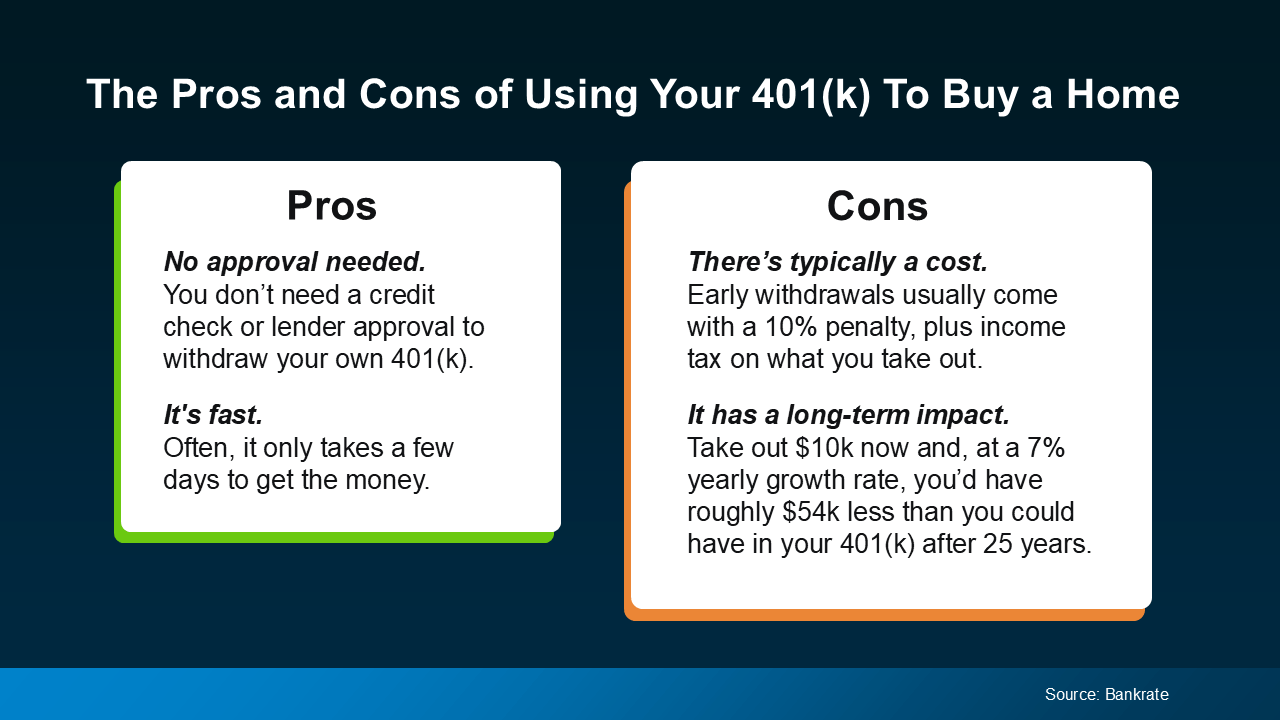
Before you decide, have a financial advisor help you compare the upsides to the risks. Bankrate points to a few of each (see visual):

a screenshot of a computer screen

Other Options Worth Exploring First

Your 401(k) isn’t the only way to finance a home purchase. Redfin outlines a few other options to look into before you decide what to do:

  • Low and No-Down Payment Loans: FHA loans, for example, allow qualified buyers to put down as little as 3.5% of the home’s price, depending on their credit scores.

  • Down Payment Assistance Programs: Many national and local programs can help reduce what you pay toward your down payment or closing costs.

Make a Plan Before You Make a Move

No matter which route you take, talk with a financial expert first. The buyers who come out ahead build a solid plan with the right professionals before starting their journey to homeownership. As NerdWallet puts it:

Even if you’re convinced a 401(k) loan is the way to go, it’s important to understand the risks at the outset.

Bottom Line

Affordability is definitely a challenge, but that doesn’t mean tapping your 401(k) is your only way in if you want to buy.

If you’re considering using your 401(k) savings for a down payment, weigh all your options and talk with a trusted financial advisor before you make any decisions. They’ll help you make a plan to fit your goals and your budget. 

Higher Rates Could Actually Help Housing Supply – Here’s How.

Higher Rates Could Actually Help Housing Supply – Here’s How. Simplifying The Market

You may have heard the number of homes for sale isn’t growing like it was. And maybe that has you worried you won’t find a home you love when it’s time to make your move.

But that may be about to change. Here’s why your pool of options may actually start ticking back up again.

Growth Has Slowed, But It Hasn’t Stopped

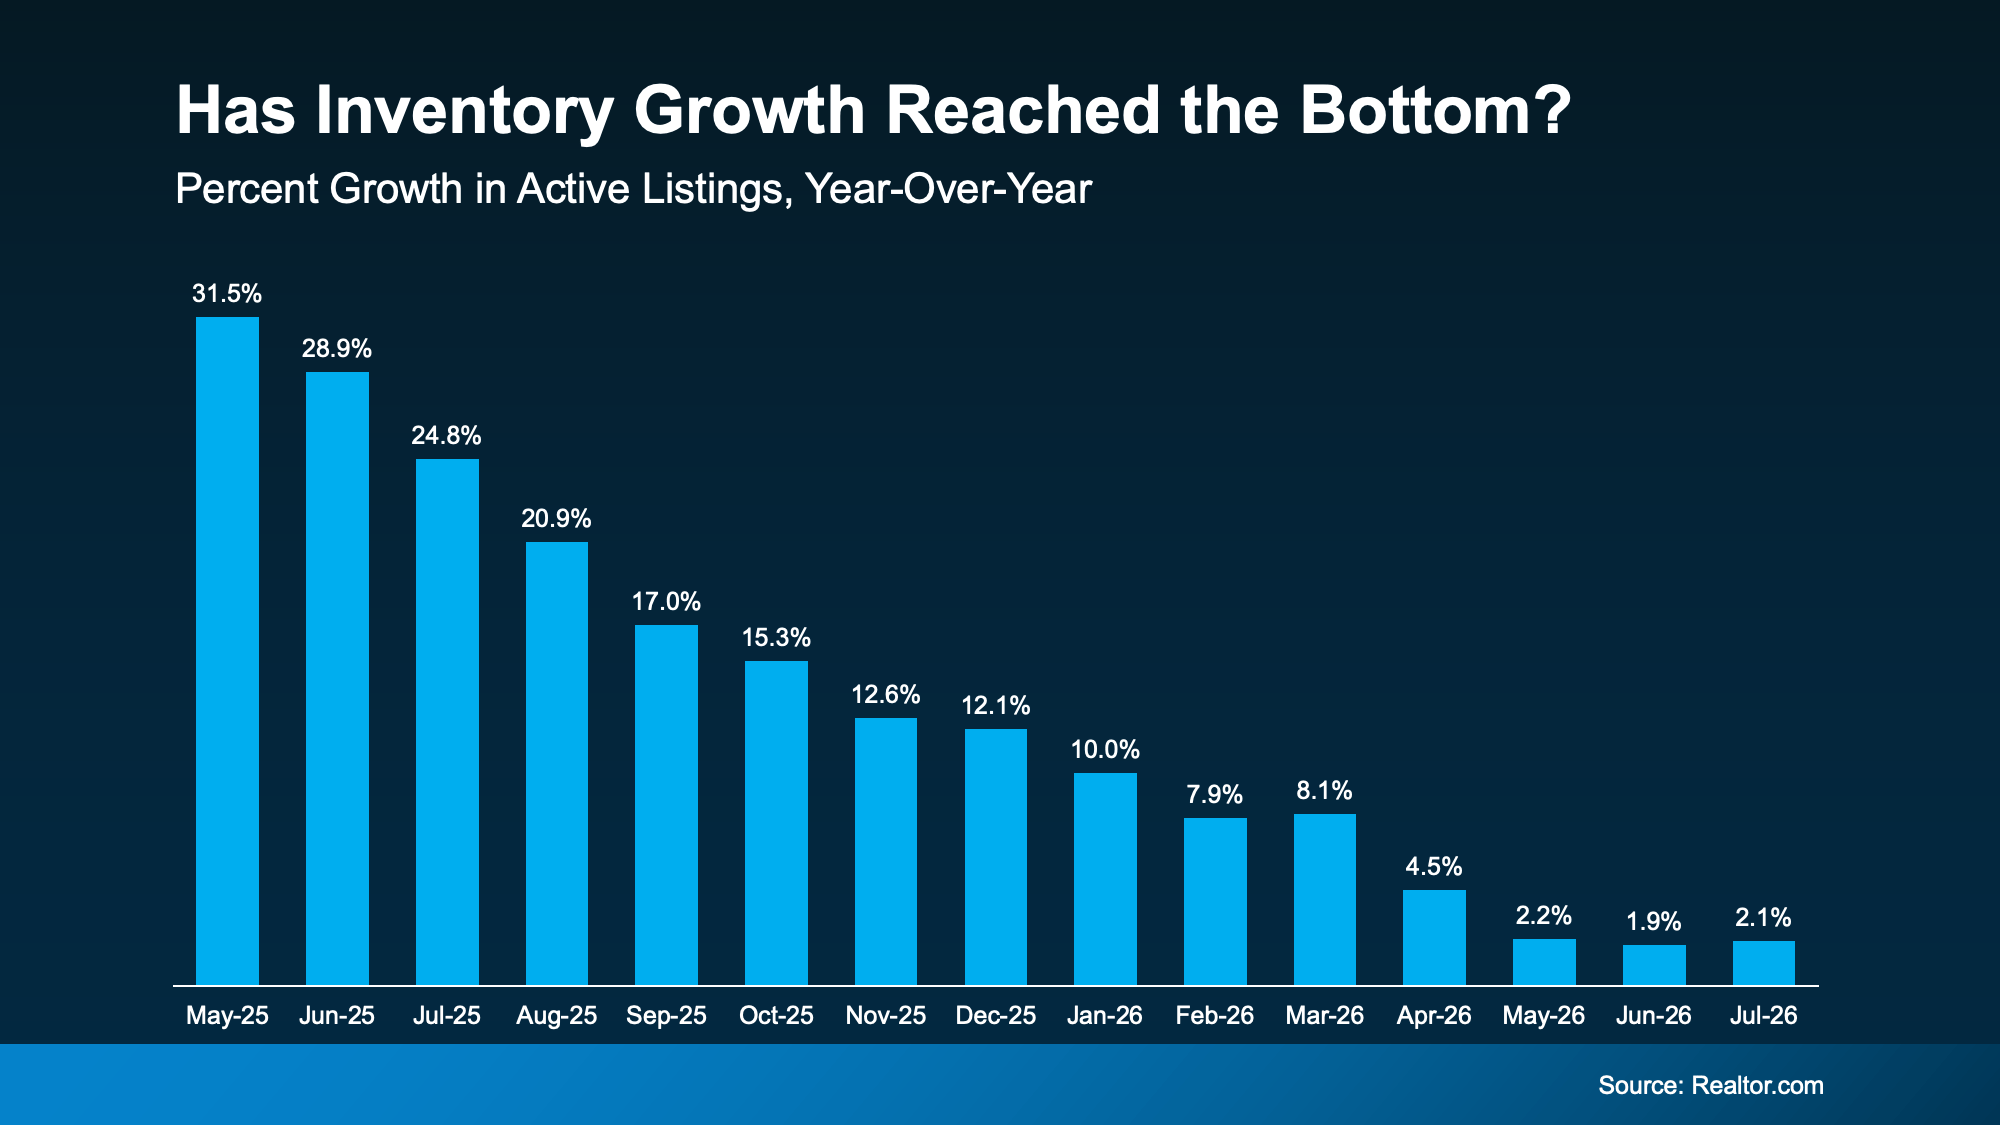
Active listings were up 2.1% year-over-year in July, according to Realtor.com. Back in January, inventory was up 10%. And in May of 2025, it was up 31.5%. So, growth has cooled off a lot over the last year.

The past 3 months, though, have all seen inventory growth land in roughly the same range, which is a sign this slowdown may be nearing its floor (see graph below):

a graph of growth in a blue background

So, what does that mean for you?

Homes are still coming onto the market. Every single one of these bars shows a period where inventory grew. So, don’t be discouraged or let this make you think you’re out of options. Plus, we’ve seen more stability in the numbers lately, which is a good sign.

The Most Homes for Sale Since 2019

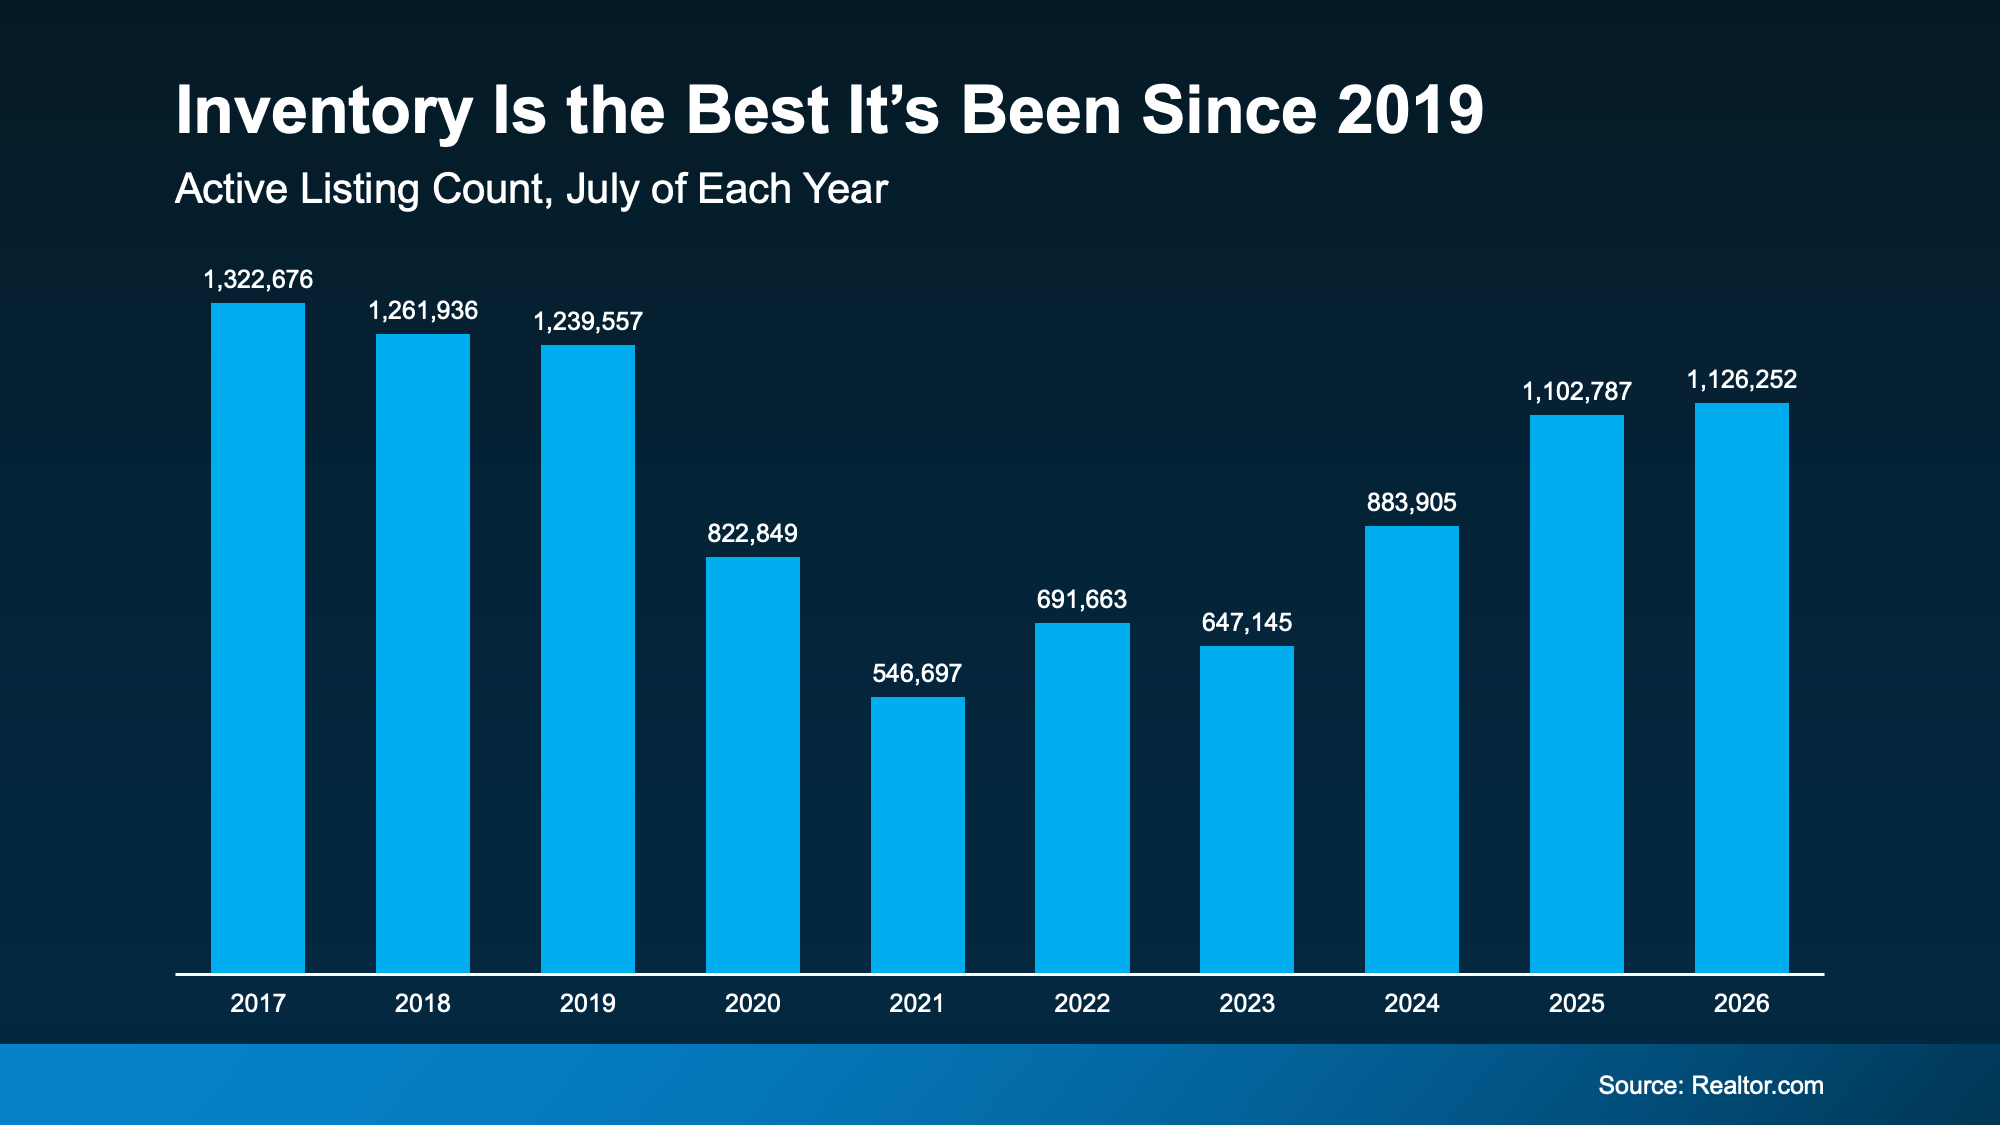
Compared to the rock-bottom lows of 2021, inventory has climbed back substantially. Nationally, the number of homes for sale has been up year-over-year consistently now for 33 months. And inventory has almost doubled in just a few years. So don’t get too hung up on the pace of that increase.

This July was actually the best July for inventory since 2019 (see graph below):

a graph of blue bars with white text

Now, the market still needs about 150k listings to get back to pre-pandemic levels, but things are quickly approaching normal. And experts think we may even be back to 2019 levels by the end of this year, even with the slowdown we’ve already seen.

And that’s thanks to one unlikely factor: mortgage rates

Why Higher Rates May Actually Help Inventory Grow

It works like this. When mortgage rates climb, inventory tends to climb with them. As Mike Simonsen, Chief Economist at Compass, explains:

When rates rise; inventory rises. When rates fall; inventory falls. So, from July last year to March this year, rates ease lower and all the inventory growth of the past several years evaporated. If rates move higher from here or stay elevated for [a] longer period of time, then we should expect supply to build again.

Well, rates are expected to hold in the mid-to-upper 6% range for a while longer, and Realtor.com‘s latest forecast has inventory ending 2026 up 3.6% year-over-year.

That means 2 things:

  • Inventory growth is forecast to pick up a little bit throughout the rest of the year.

  • And, inventory is projected to close the year at a historically normal level, right about where it stood at the end of 2019.

For buyers, that’s a win. Even if today’s rates aren’t your favorite, they’re helping the number of homes on the market to grow. And more homes for sale means more choices, more room to negotiate, and less pressure to rush your search.

Bottom Line

The number of homes for sale is growing slowly but surely, and that means more options for your move. Want to see what’s available in your area? Reach out to a local real estate agent.

Who Has the Upper Hand in Today’s Housing Market?

Who Has the Upper Hand in Today's Housing Market? Simplifying The Market

Ask around and almost every homebuyer out there wants to know if there’s a way to get a better deal. And just about every seller wants to know if they’ll still get top dollar.

The interesting thing is… both can be right at the exact same time. It just depends on where you live.

That’s because today’s housing market isn’t moving in one direction anymore. Some markets clearly favor buyers. Others still favor sellers. But most are sitting somewhere in the middle.

And knowing which market you’re actually in can completely change the strategy you use to buy or sell (and what expectations you should have). Let’s break it down.

One Number Tells You Who’s Got Leverage

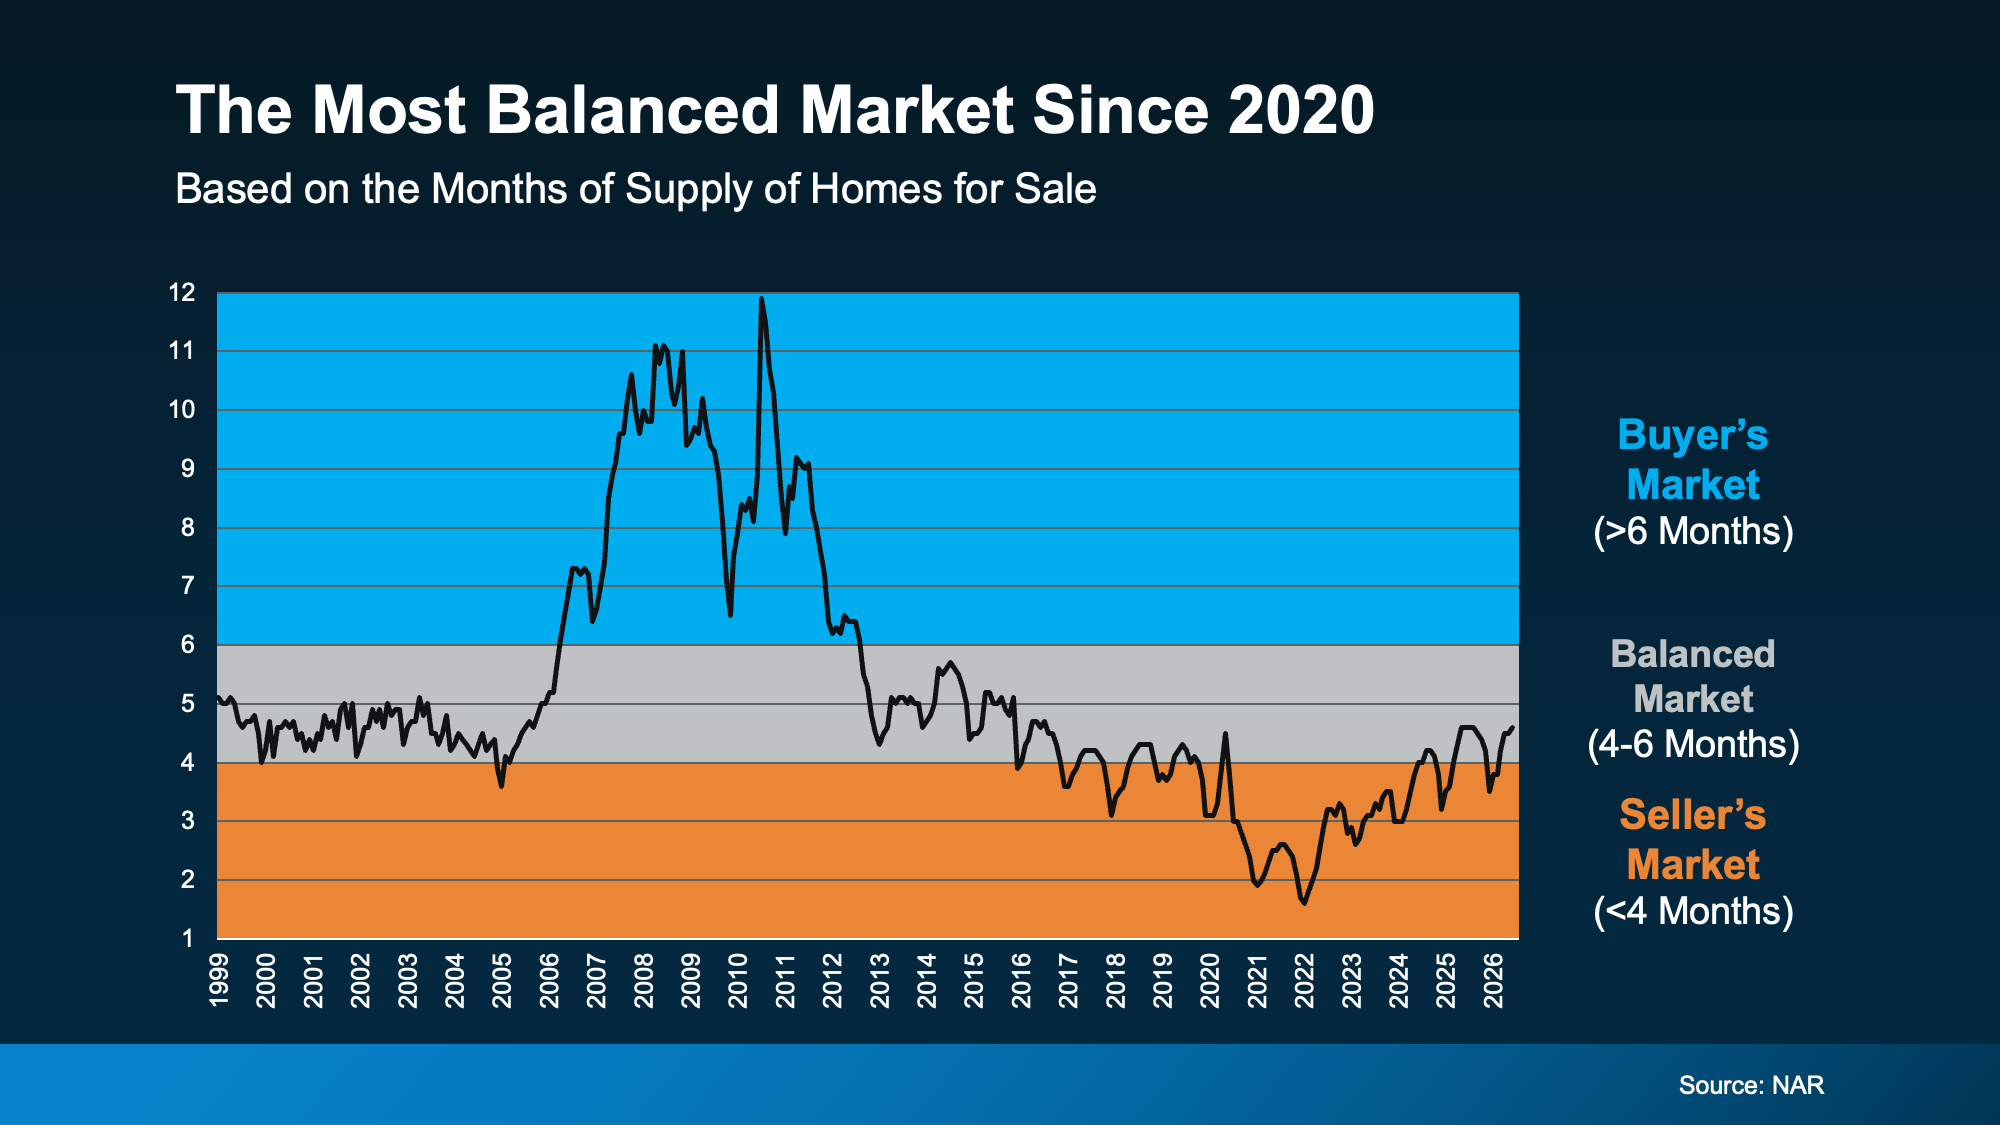
So how do you know which market you’re in? There’s one number that tells the story faster than anything else: the months’ supply of homes for sale. It’s the clearest signal of who’s got leverage – and what strategy you’ll need. Think of it like this.

Imagine no additional homes were listed starting today. Months’ supply tells us how long it would take to sell everything that’s currently on the market based on today’s demand. 

Generally speaking, if months’ supply is:

  • Fewer than 4 months: Sellers usually have the advantage.

  • 4 to 6 months: Buyers and sellers are on more equal footing.

  • More than 6 months: Buyers can usually negotiate for a better deal.

Right now, the National Association of Realtors (NAR) data says that number is 4.6 and that puts the overall market back in balanced territory (see graph below):

a graph of a market

That means, as a whole, the market has finally moved back into a much more balanced range after years of being tilted in sellers’ favor. While that may look like the scales have tipped only slightly, it’s enough to make a real difference in what strategy you’ll need for your move – at least in most places.

The Tale of Two Markets: Why ‘Balanced’ Doesn’t Mean the Same Thing Everywhere

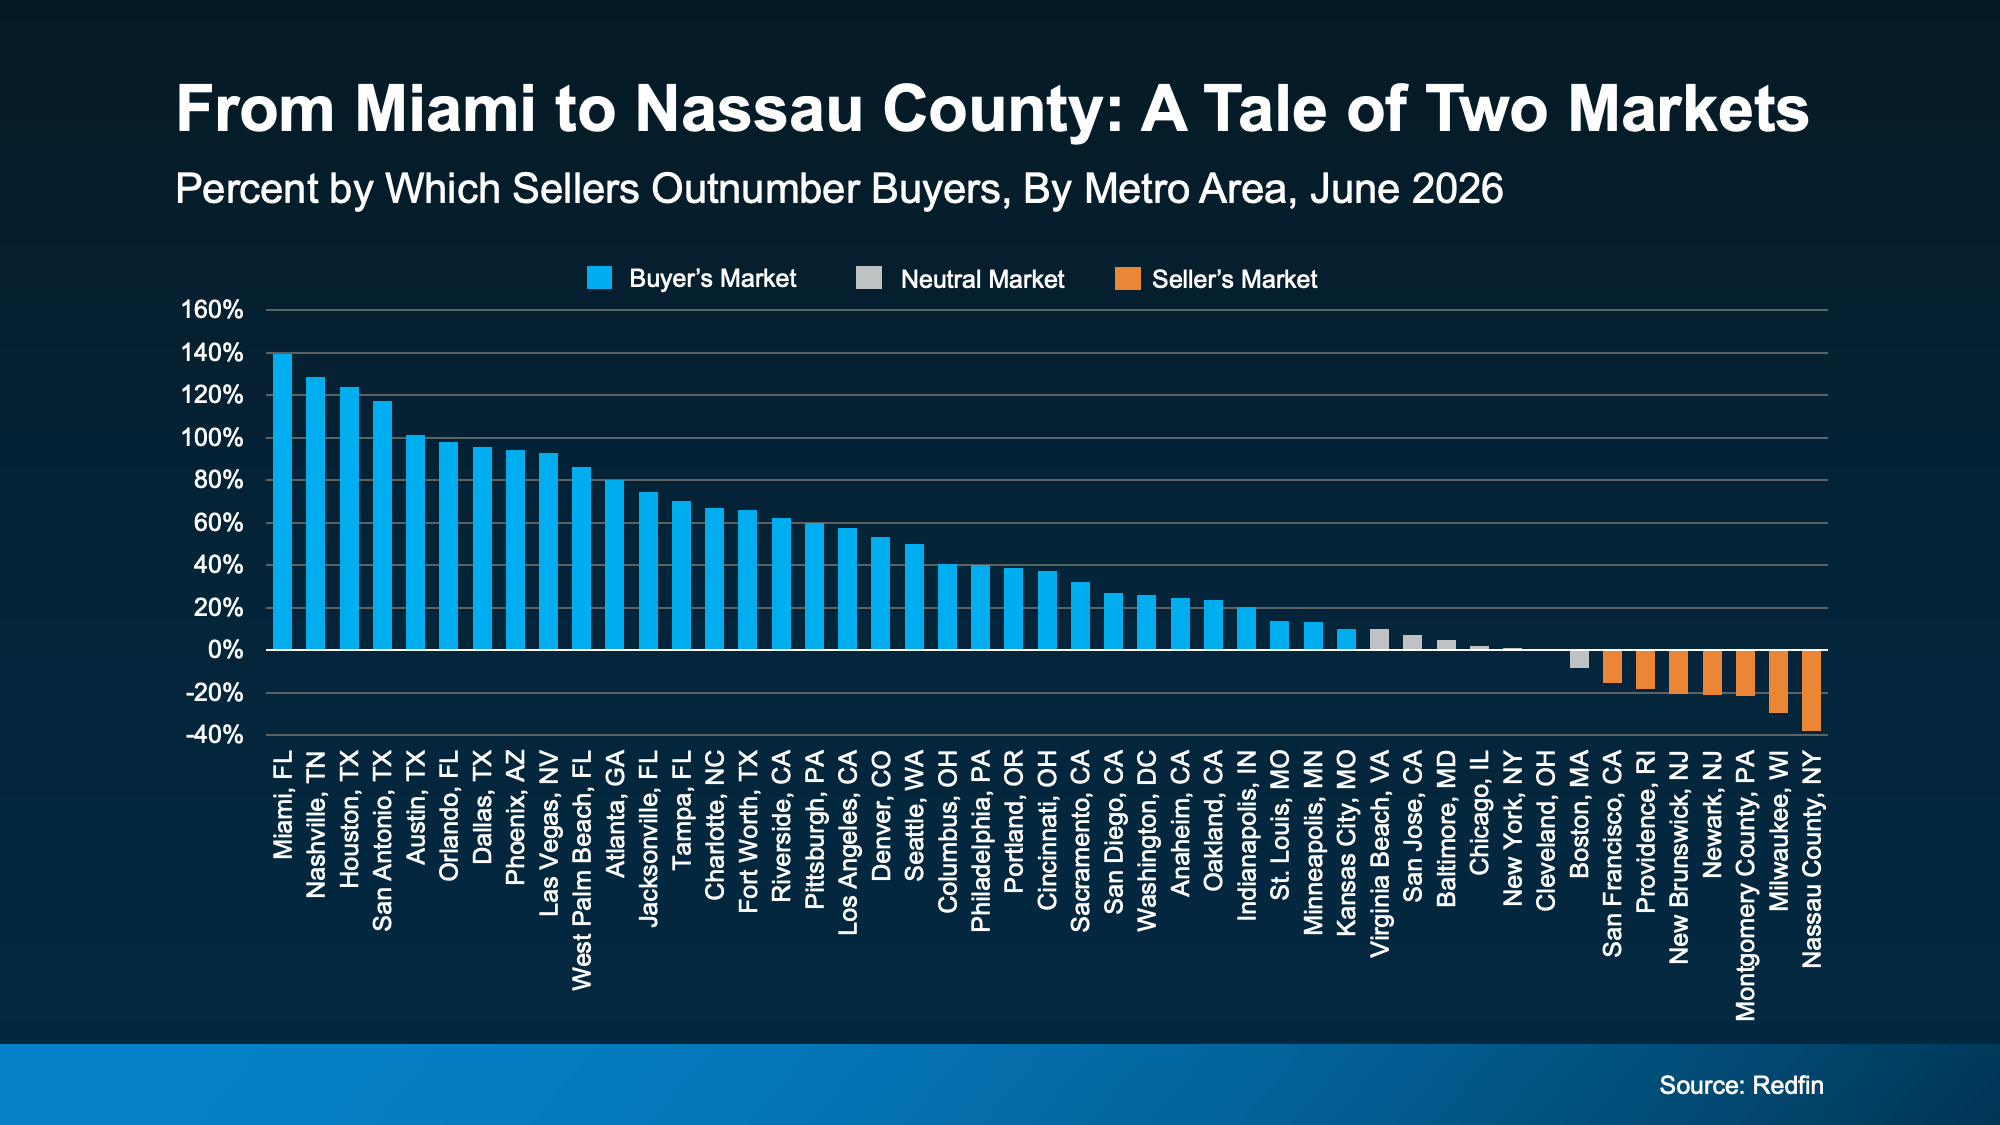
Redfin data helps shed some light on how this shakes out across the country. It breaks down which cities are leaning in either direction (see graph below).

  • Some markets give buyers more leverage. Those are in blue.

  • Some still favor sellers. That’s the orange.

  • Others fall somewhere in between. Those are gray. 

a graph of a marketNotice anything? A lot more places are seeing more buyer-friendly conditions right now.  In fact, this is the most buyer-friendly market we’ve seen in nearly 6 years.
But don’t take that as buyers have the upper hand everywhere.

There are still cities where sellers still have the power. And if you’re in one of them, your approach to selling or buying looks completely different than it would in a buyer-leaning market.

The Biggest Mistake You Can Make Right Now

That’s why the biggest mistake isn’t thinking it’s finally a buyer’s market. And it isn’t thinking it’s still a seller’s market either. It’s making any assumption without talking to an expert agent first.

Today’s market is incredibly local. In one market, a buyer may be getting thousands of dollars in concessions from a seller. And a homeowner may have to consider dropping their price.  

But in another, a buyer may be stressed about coming in with their best offer, or they may lose out on the home to another buyer. And a seller may still be seeing strong demand and prices inching higher.

Same overall housing market.

Very different experiences.

The truth is what’s happening in your back yard affects everything from pricing your house to making an offer to negotiating repairs or concessions. And that’s why an agent’s local knowledge matters more now than ever before.

Your plan has to be based on your neighborhood – and only an agent has the expertise to get that right.

Bottom Line

This market isn’t one-size-fits-all.

If you’re wondering who has the upper hand where you live, talk to a local agent. They’ll help you understand what’s happening in your market, who’s got the leverage, and what strategy gives you the best shot at getting what you want.

Here’s Why Mortgage Rates Are What They Are Right Now

Here’s Why Mortgage Rates Are What They Are Right Now Simplifying The Market

If you’re waiting for mortgage rates to fall a lot before you buy, you may be waiting a while. But before you get discouraged, there’s a number working behind the scenes that’s actually good for you right now. It’s called the spread, and once you understand it, you may see today’s rates in a whole new light.

The Pattern That’s Held for 50+ Years

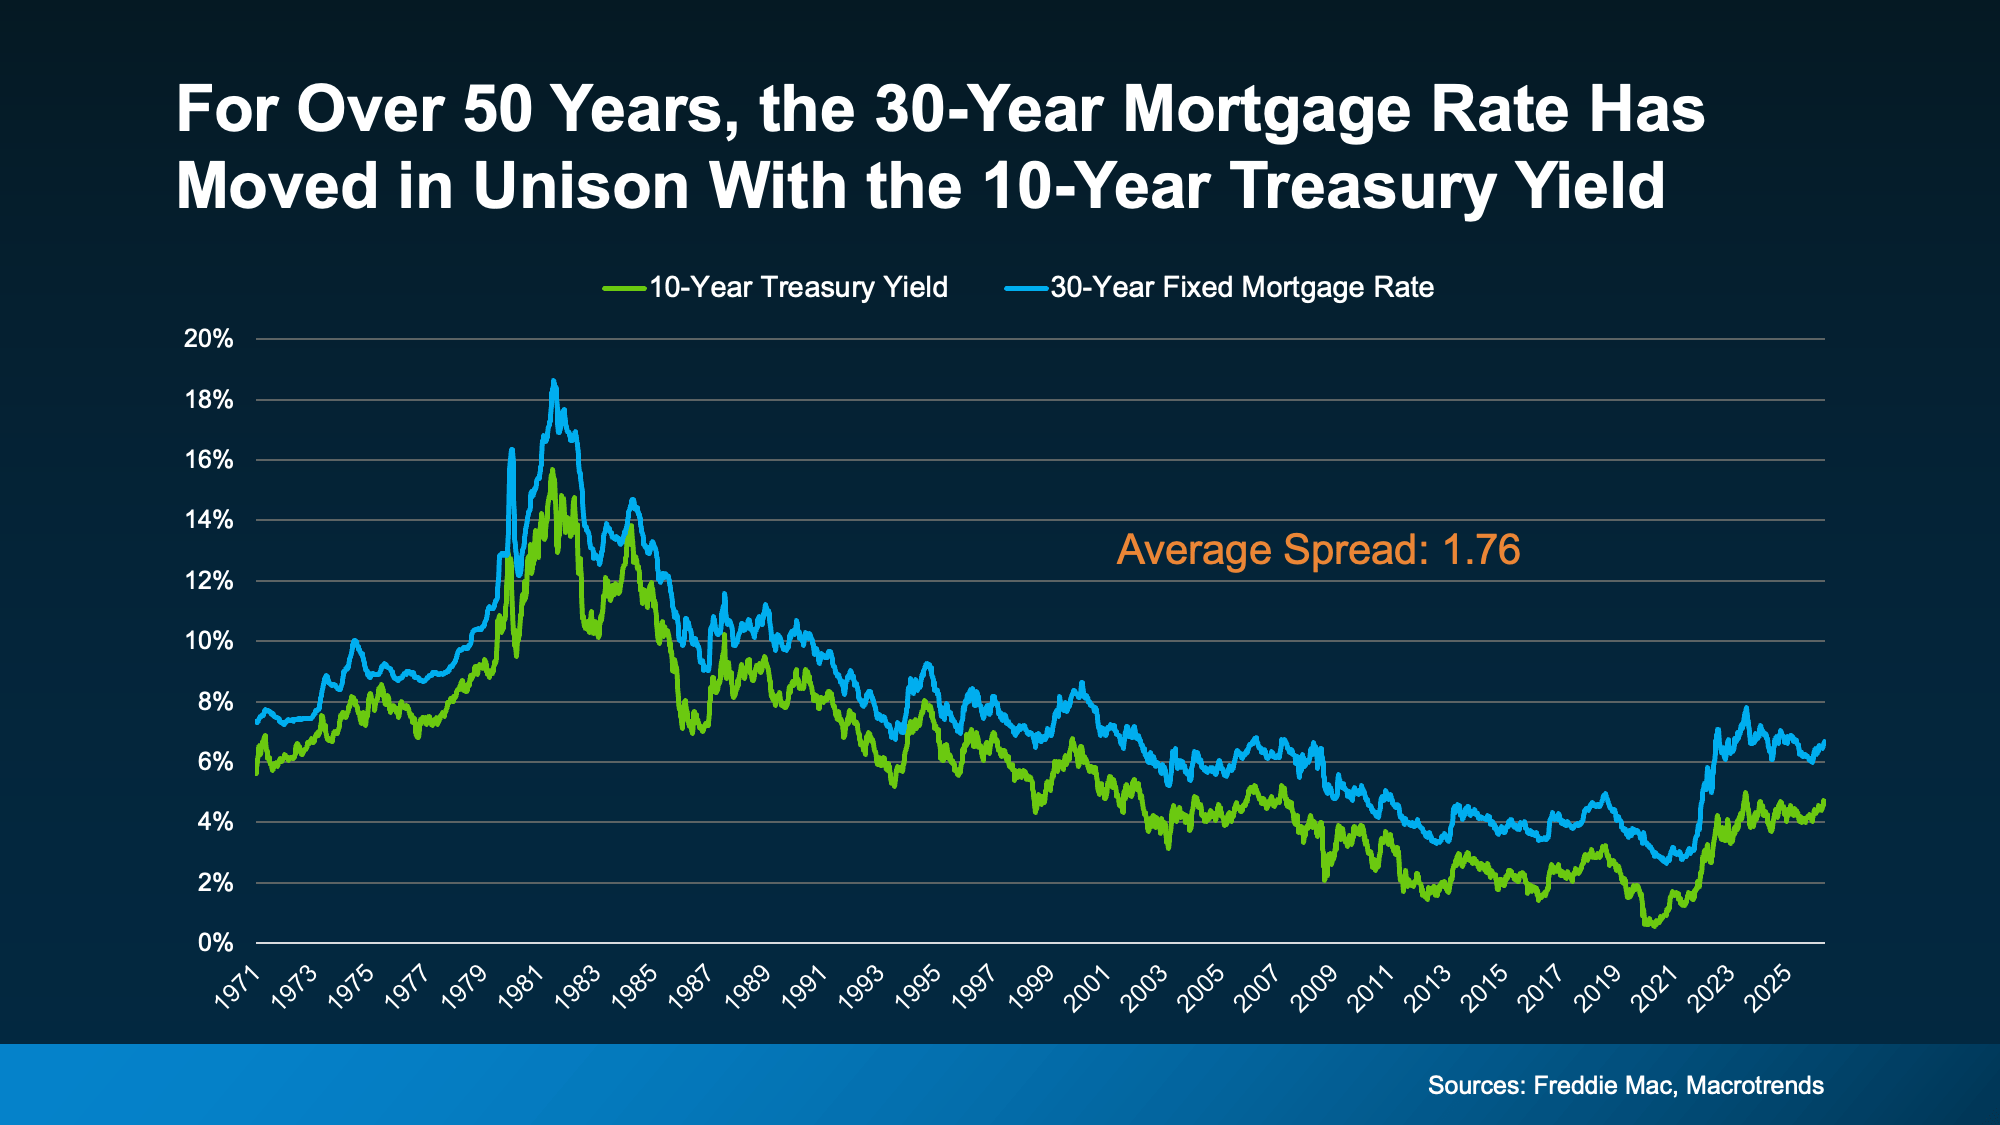
For starters, mortgage rates don’t move on their own. They tend to follow the 10-year treasury yield, a number tied to how investors feel about the economy.

It’s not an exact science, since plenty of other factors can move it day to day, but broadly speaking, when the economy looks strong, that yield tends to climb over time. When the outlook gets shaky, it tends to ease. For over 50 years, the 10-year treasury yield and mortgage rates have moved almost in lockstep (see graph below):

a graph of a graph showing the number of mortgage rates

The gap between them is called the “spread.” On average, that gap runs about 1.76 percentage points. And that spread impacts your mortgage rate. A wider spread tends to push mortgage rates higher than the treasury yield alone would suggest, while a narrower spread keeps rates closer to the treasury yield.

One of the Big Reasons Rates Likely Won’t Drop Dramatically Anytime Soon

If you’re hoping mortgage rates will drop a lot, here’s the reality – they probably won’t, at least not anytime soon. One of the big reasons why comes down to that spread between the 10-year treasury yield and mortgage rates.

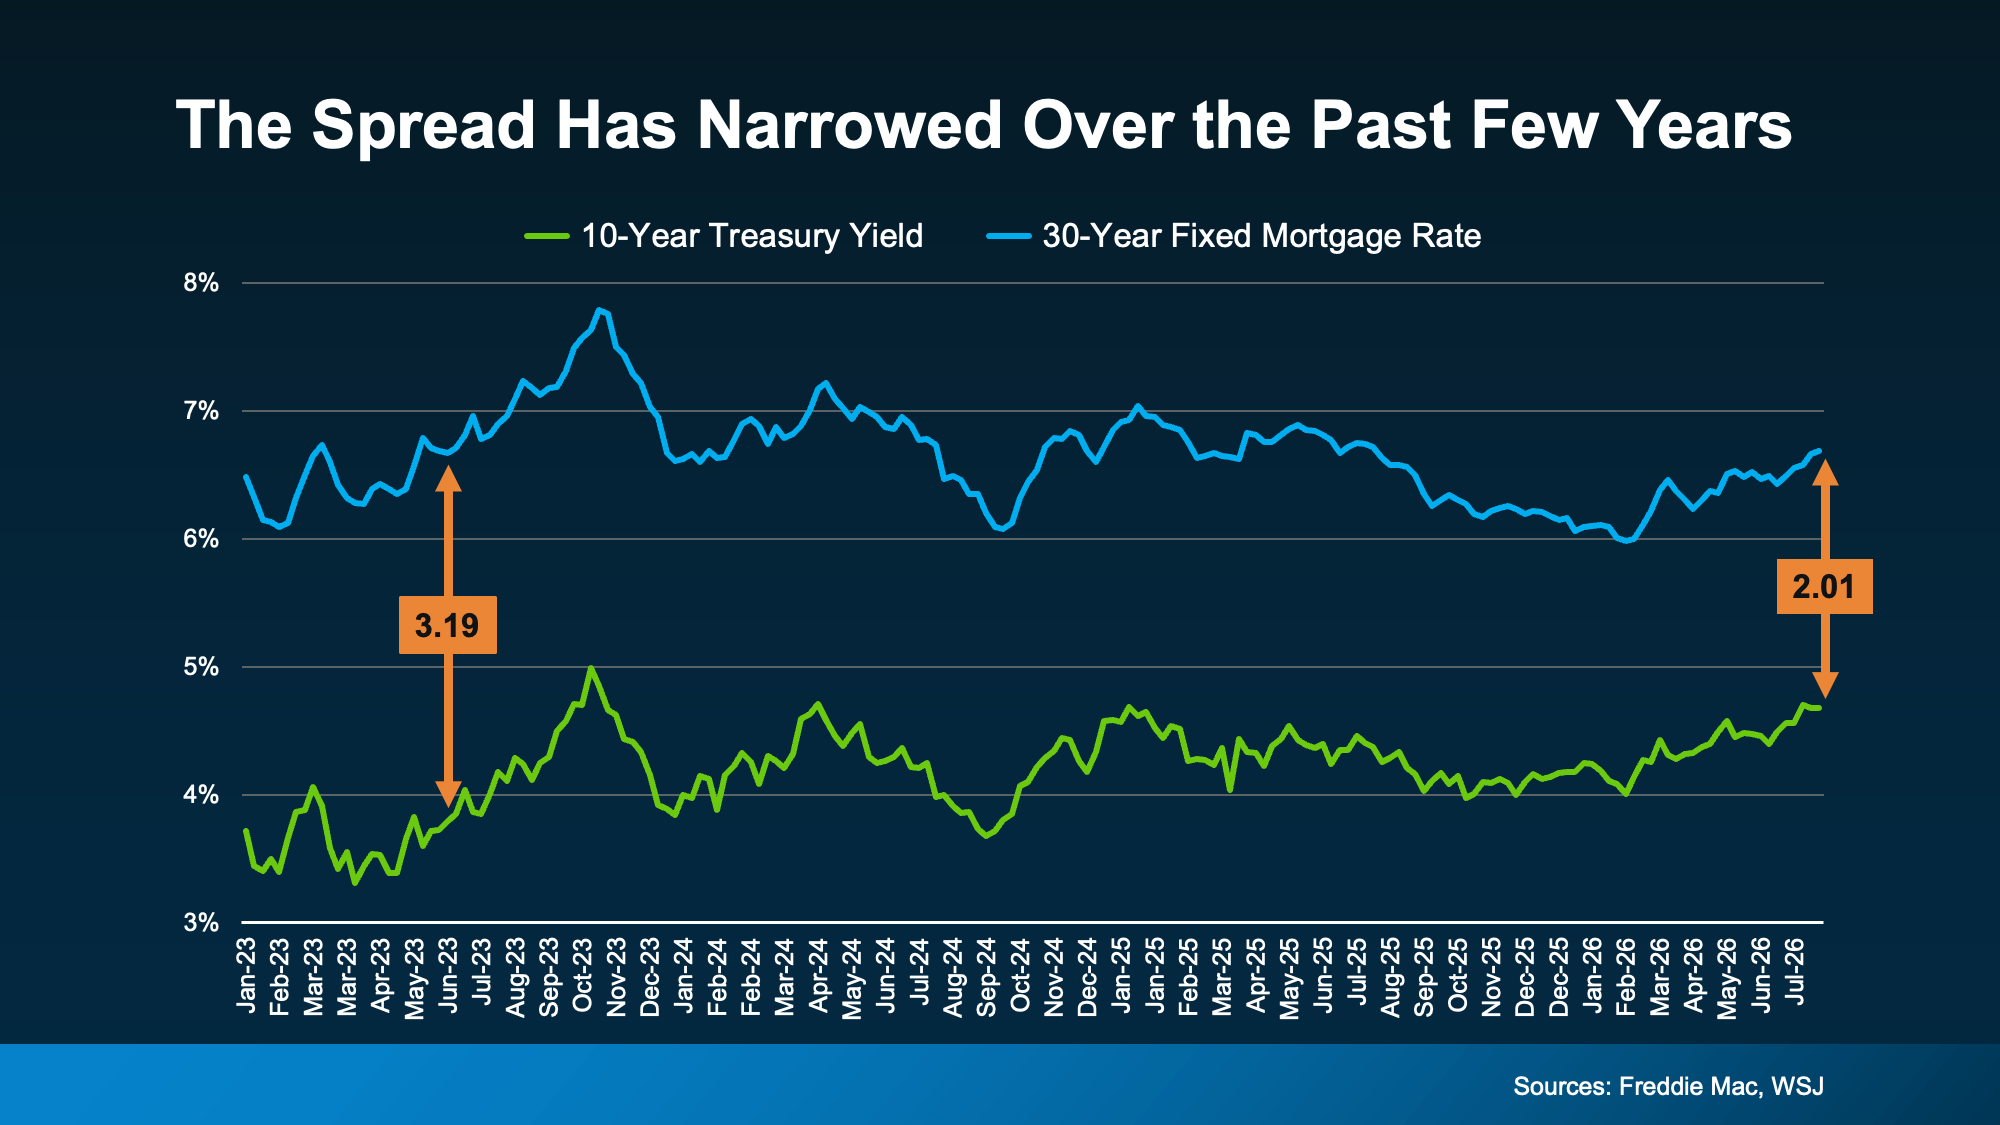
A few years ago, that gap got a lot wider as uncertainty in the economy pushed it as high as 3.19 points in 2023.

Now here’s the part worth noting – that gap has been narrowing lately. It’s down to about 2.01, just above the long-term average of 1.76 (see graph below):

a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of

When the gap is wide, there’s more room for rates to fall. But when it’s relatively normal, like it is now, there’s less wiggle room for rates to fall.

Why Mortgage Rates Aren’t Higher Right Now

Today’s mortgage rate is basically the treasury yield plus the spread. So, when either one moves, your rate moves with it. Here are 3 different rates, all built off today’s 10-year treasury yield of 4.68% to show you just how much the spread matters for your bottom line (see graph below):

a graph of a graph showing a rate of interest

If the spread were still stretched out like it was in 2023, rates would be pushing close to 8% right now. That’s because the spread was over a full point wider than it is today.

But now, thanks to the spread narrowing recently, today’s rate sits around 6.69%. That’s the middle scenario in that visual. That’s a big difference in your monthly payment compared what we could see if the spread was as big as it was 2023. As Logan Mohtashami, Lead Analyst at HousingWire, put it:

“Of course, mortgage spreads being better in 2026 is the housing hero story of the year . . .”

Now compare that middle bar to the 3rd one. If the spread were sitting at its exact long-term average, rates would be around 6.5%. That’s only about a quarter of a point away from where rates actually are today. That means most of the improvement in mortgage rates we should realistically expect from a shrinking spread has already happened.

In other words, the same narrowing spread that’s the reason rates aren’t close to 8% today is also a big reason why they’re not likely to fall a lot further.

Bottom Line

That’s the trade-off with a narrowing spread. Rates may not be where you want them, but they’re better than they could’ve been. If you want help figuring out what that means for your monthly payment, reach out to a local lender

Think You Have To Put 20% Down? Most First-Time Homebuyers Don’t.

Think You Have To Put 20% Down? Most First-Time Homebuyers Don’t. Simplifying The Market

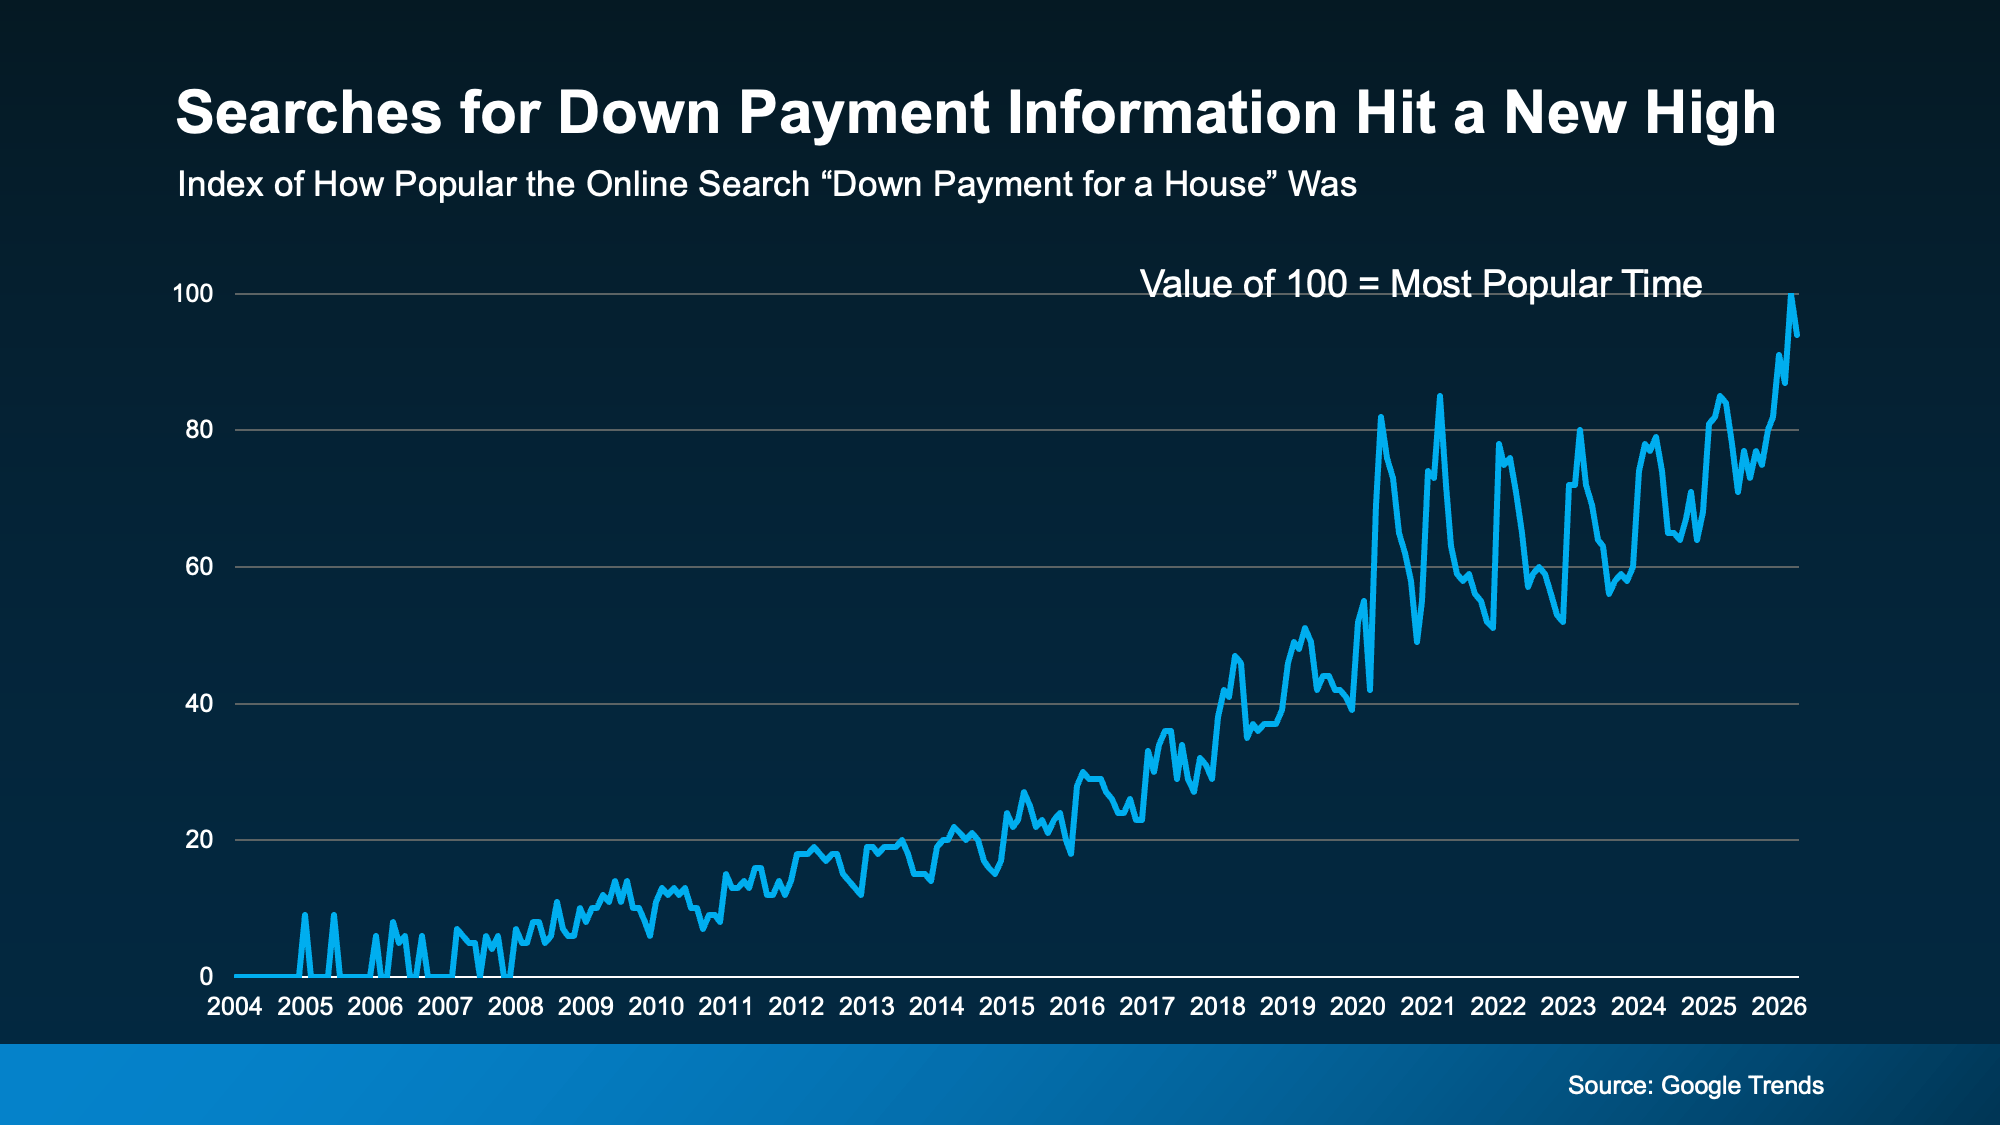
According to Google Trends, online searches for down payment information recently hit an all-time high. And that’s a clear sign more buyers are trying to figure out what they really need to save before making a move (see graph below):

a graph of a line graphIf you’re wondering the same thing, you can always turn to the internet for answers. But a lot of the time, it’s better to ask a local expert. Because here’s what a pro would tell you.

The 20% Down Payment Myth

The idea that you need 20% down to buy a home is one of the biggest misconceptions around the homebuying process. And the data debunks the myth.

While there are benefits to putting that much money down, most first-time buyers put down far less.

Here’s why. Unless it’s stated by your lender, you typically don’t have to have a 20% down payment. There are even some loan options designed to help you get into a home with a much smaller upfront cost. As the Mortgage Reports explains:

“The amount you need to put down will depend on a variety of factors, including the loan type and your financial goals. If you don’t have a large down payment saved up, don’t worry—there are plenty of options available, and you don’t need to put down the traditional 20% . . . many homebuyers are able to secure a home with as little as 3% or even no down payment at all . . .

For example, FHA loans allow down payments as low as 3.5%, while VA and USDA loans offer zero down payment options for qualified applicants, like Veterans.

And those options are just one reason so many first-time buyers are able to buy without a 20% down payment.

What Buyers Are Actually Putting Down

So, if buyers aren’t doing 20%, how much do they actually put down?

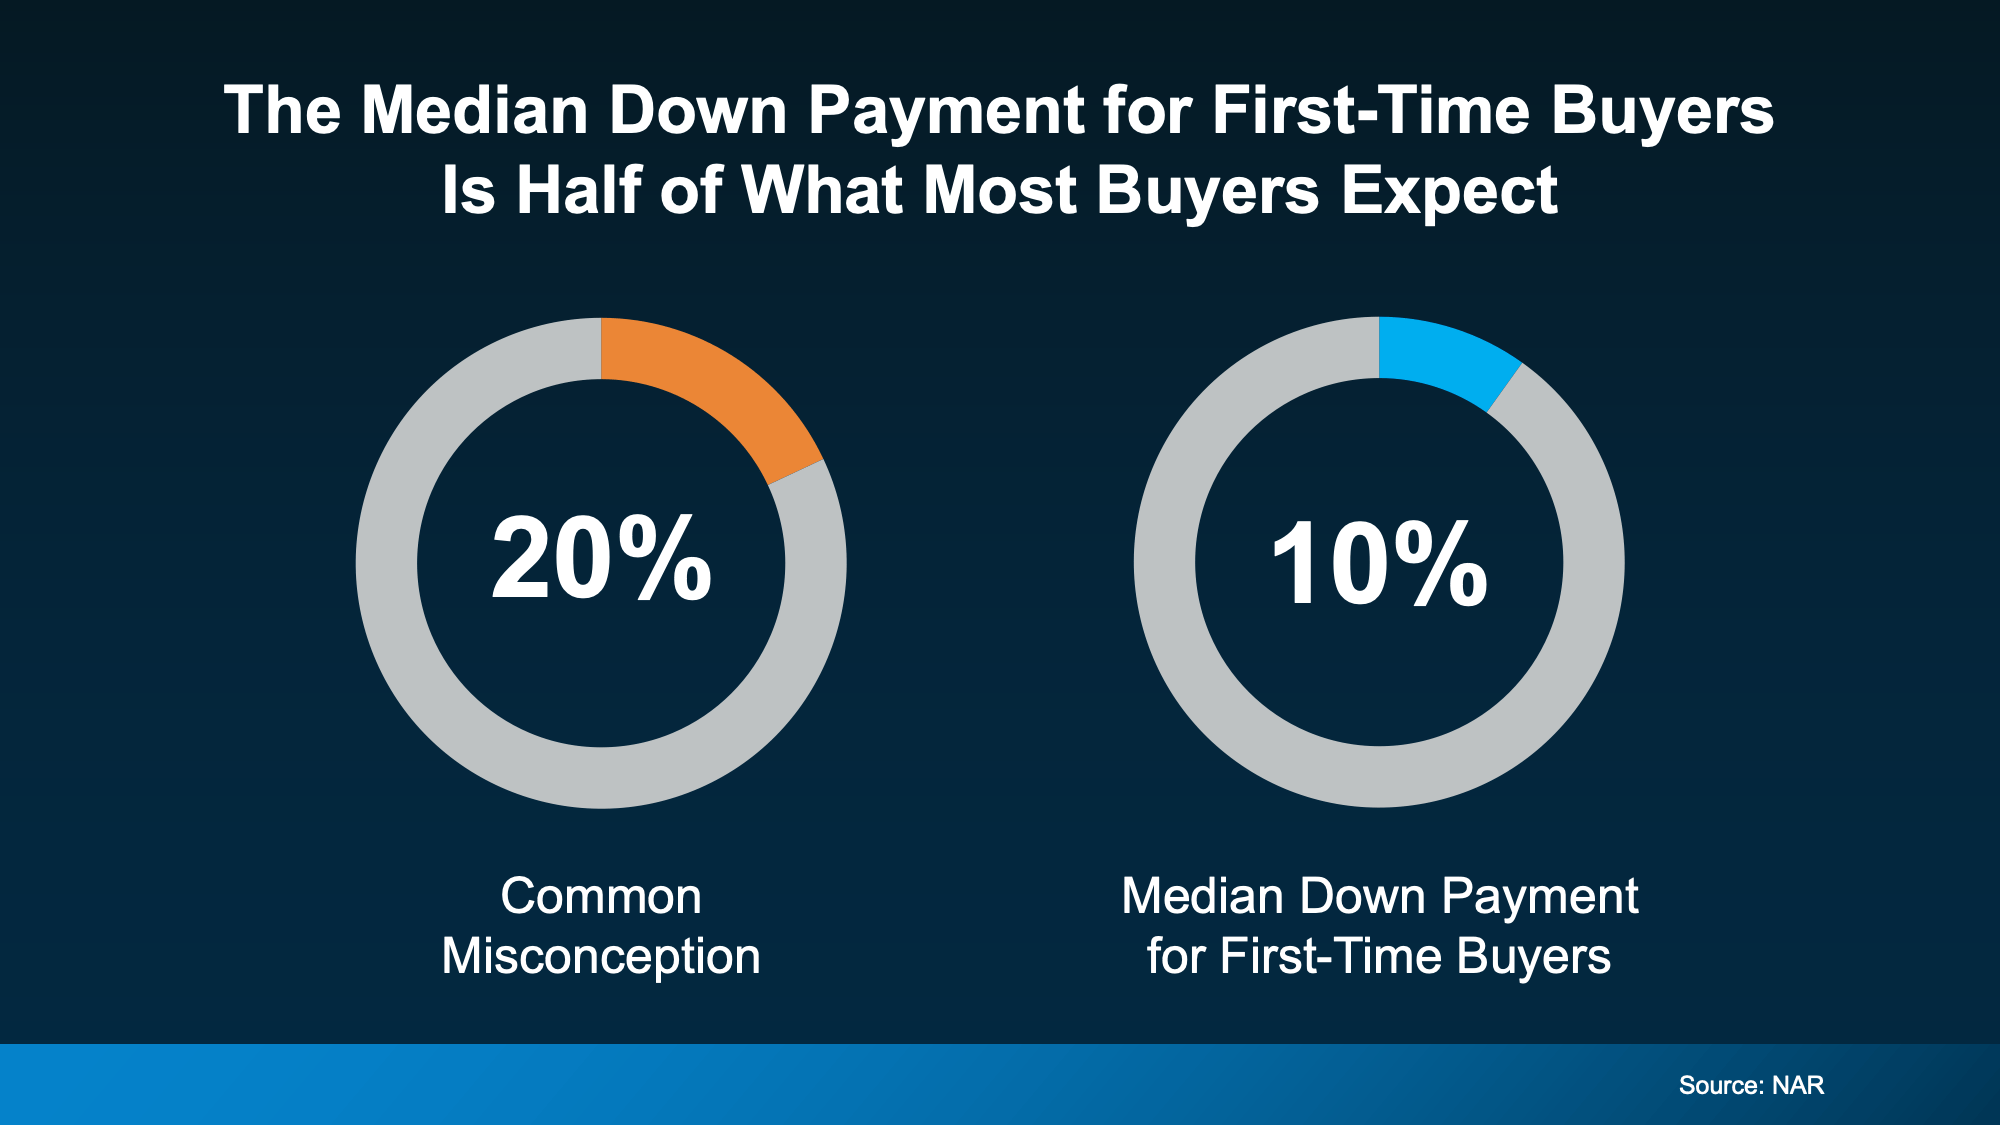
According to the National Association of Realtors (NAR), the median down payment for first-time homebuyers is only 10%. That’s half of what you probably expected.

a diagram of a pie chartThat means if you’re aiming to save 20% because you think you have to, you may be setting a timeline that’s longer than necessary.  

And here’s some more good news. It’s not only that you may be able to buy with less money down than you thought, but there are also options to help you get to your down payment goal even faster.

Why You Should Look into Down Payment Assistance Programs

There are a lot of programs designed to help you save for a down payment – and they can make a big difference in how fast you hit your savings target. Unfortunately, buyers don’t realize how many there are, or that they may qualify for help.

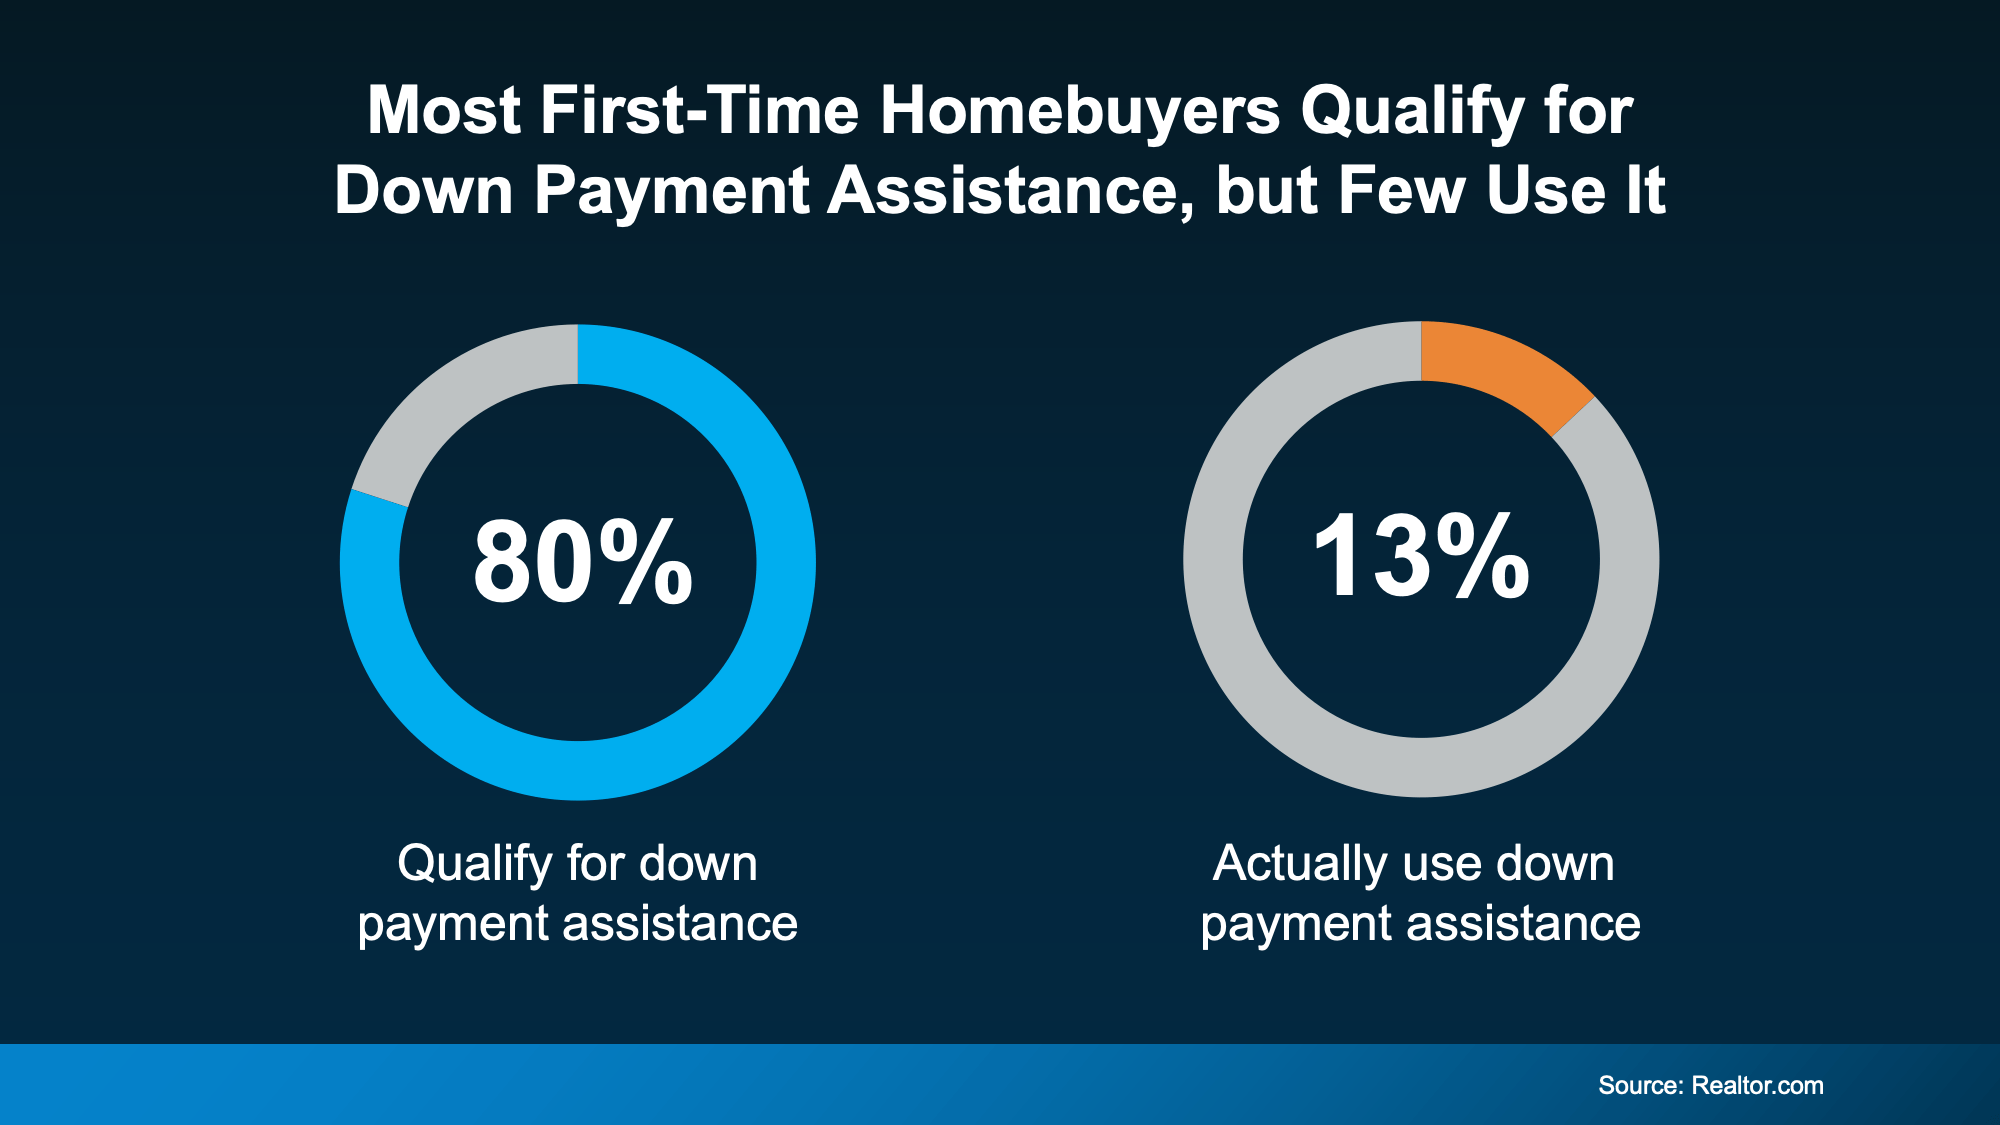
Research from Realtor.com shows almost 80% of first-time homebuyers qualify for down payment assistance (DPA), but only 13% actually use it (see chart below)

a blue and orange pie chartAnd that’s another big miss holding would-be buyers like you back.

In the U.S., there are over 2,600 homeownership programs available, many offering significant financial support. As Down Payment Resource shares:

With an average benefit of $18,000, down payment assistance (DPA) remains one of the most essential tools for addressing the nation’s affordability challenges. Programs continue to expand in scope, serving a broader range of incomes, property types and borrower needs, including first-generation, military and repeat buyers.

Imagine how much further your savings could go with an extra $18,000 you can use to buy. In some cases, you may even be able to stack multiple programs, giving what you’ve saved an even bigger boost.

Bottom Line

The simple truth is: most first-time buyers don’t put 20% down. And if you’ve been waiting to buy until you have that saved, you may be setting a timeline that’s longer than necessary.

To find out what you really need to save and if you qualify for any help, connect with a trusted lender who can walk you through your options. You may be able to buy sooner than you thought.

3 Things That Are Not Going To Happen in Today’s Housing Market

3 Things That Are Not Going To Happen in Today's Housing Market Simplifying The Market

There’s a lot of uncertainty right now and that’s leading to some dramatic headlines. And if you’re thinking about buying a home, that can make you feel a little less sure about your decision.

A recent study by CNBC asked homebuyers what they’re most worried about, and three themes kept coming up again and again:

  • Mortgage rates
  • The number of homes for sale
  • Home prices

But a lot of what you may be hearing on those is based more on misconceptions. Not facts. So, let’s break it down and separate fact from fiction.

Misconception #1: “I’ll Just Wait, Because Mortgage Rates Are Going To Fall Dramatically”

One idea doing its rounds on social is that mortgage rates are going to drop dramatically soon. So, it’s better to wait to buy.

But is that really what’s expected?

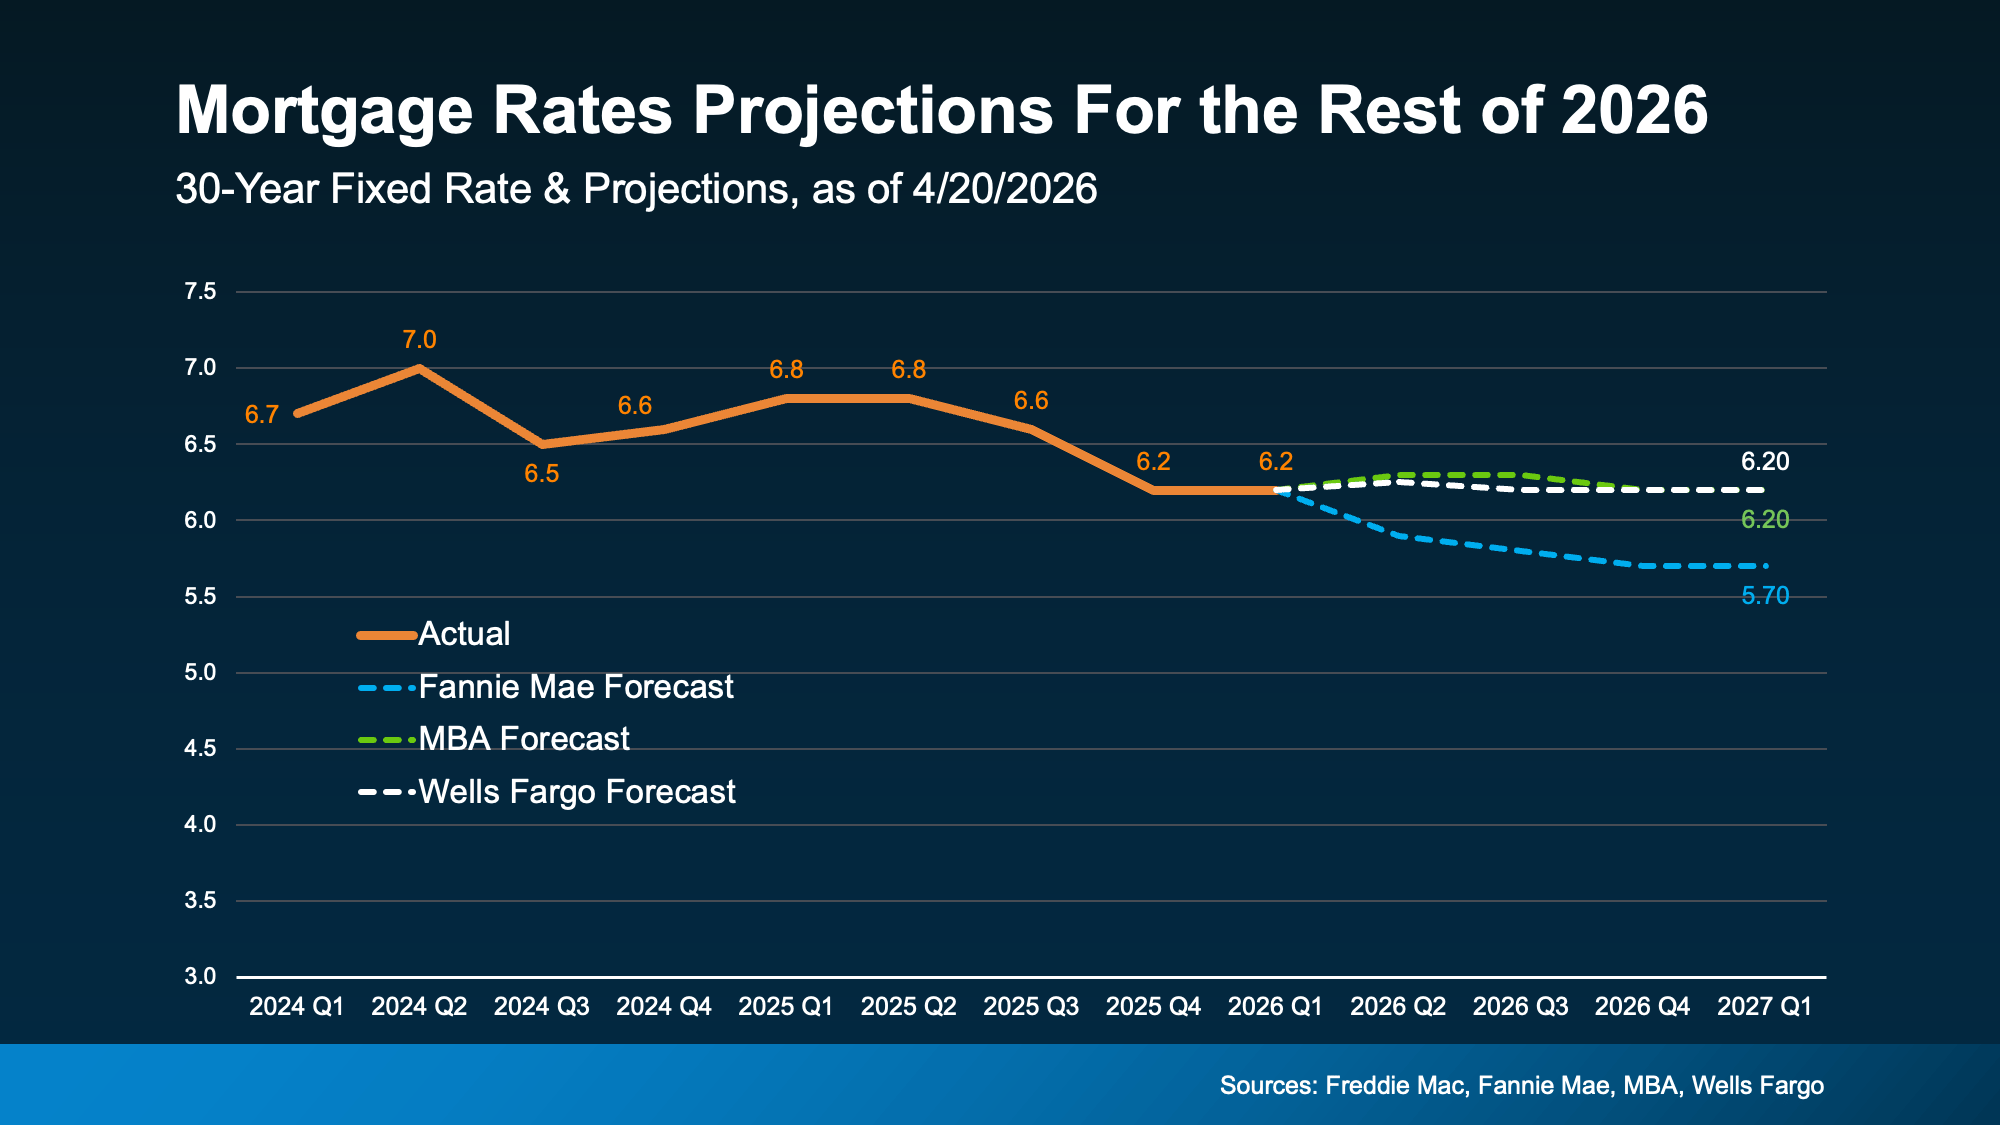
While mortgage rates have come down a bit in the last few weeks, forecasts don’t show a major drop ahead. The most likely scenario is that rates stay somewhere in the low 6% range this year. 

And that’s not a big change from where rates are now (see graph below): 

a graph with numbers and linesOf course, this depends on where inflation and the economy go from here. But, based on what we know today, waiting for a big drop in rates may not work out the way some people hope. As U.S. News explains:

“Mortgage rates aren’t expected to change much over the next several quarters . . .”

Not to mention, even with rates where they are today, it’s already more affordable than a year ago. So, even if they don’t change much, it’s still better than it was.

Misconception #2: “There Are Too Many Homes for Sale Right Now”

You’ve probably heard inventory is up. And nationally, it is. The number of homes for sale is 8% higher than this time last year. But that’s not a bad thing. In fact, it’s one of the reasons buyers have a bit more breathing room right now.

The problem is the headlines are making something good, sound bad. They’re focusing on how this is the most inventory we’ve had since 2019 or how many homes builders are building. And that can make it sound like the number of homes for sale is rising too far, too fast.

But that’s not what the bigger picture shows.

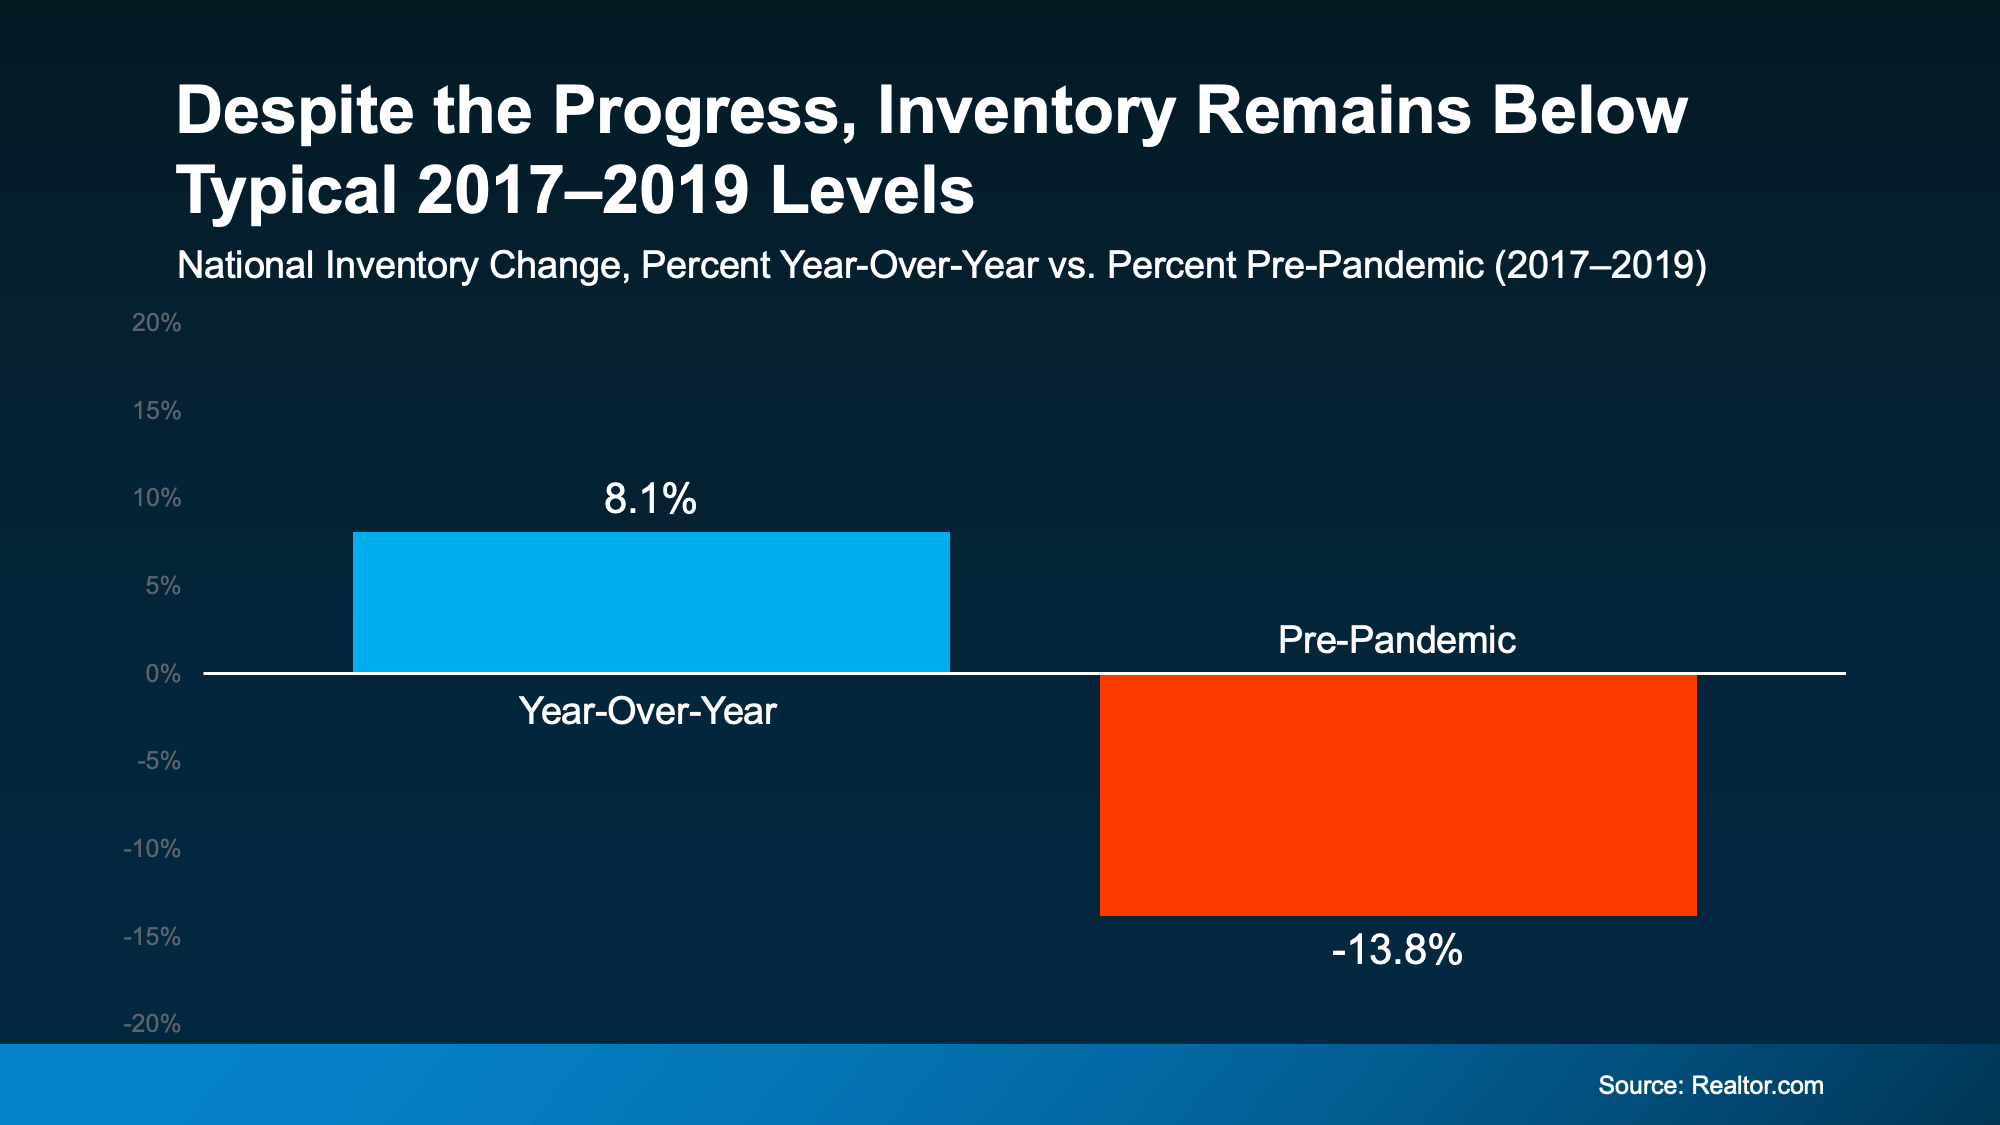
Data from Realtor.com proves that, even though inventory is up compared to last year, it’s still nearly 14% lower than it was during the last normal housing market (2017-2019):

While it can vary a lot based on where you live, only 9 states have more inventory than pre-pandemic today. That’s a key reason why there still aren’t enough homes for sale to trigger something like the crash back in 2008.
Misconception #3: “Home Prices Are About To Crash”

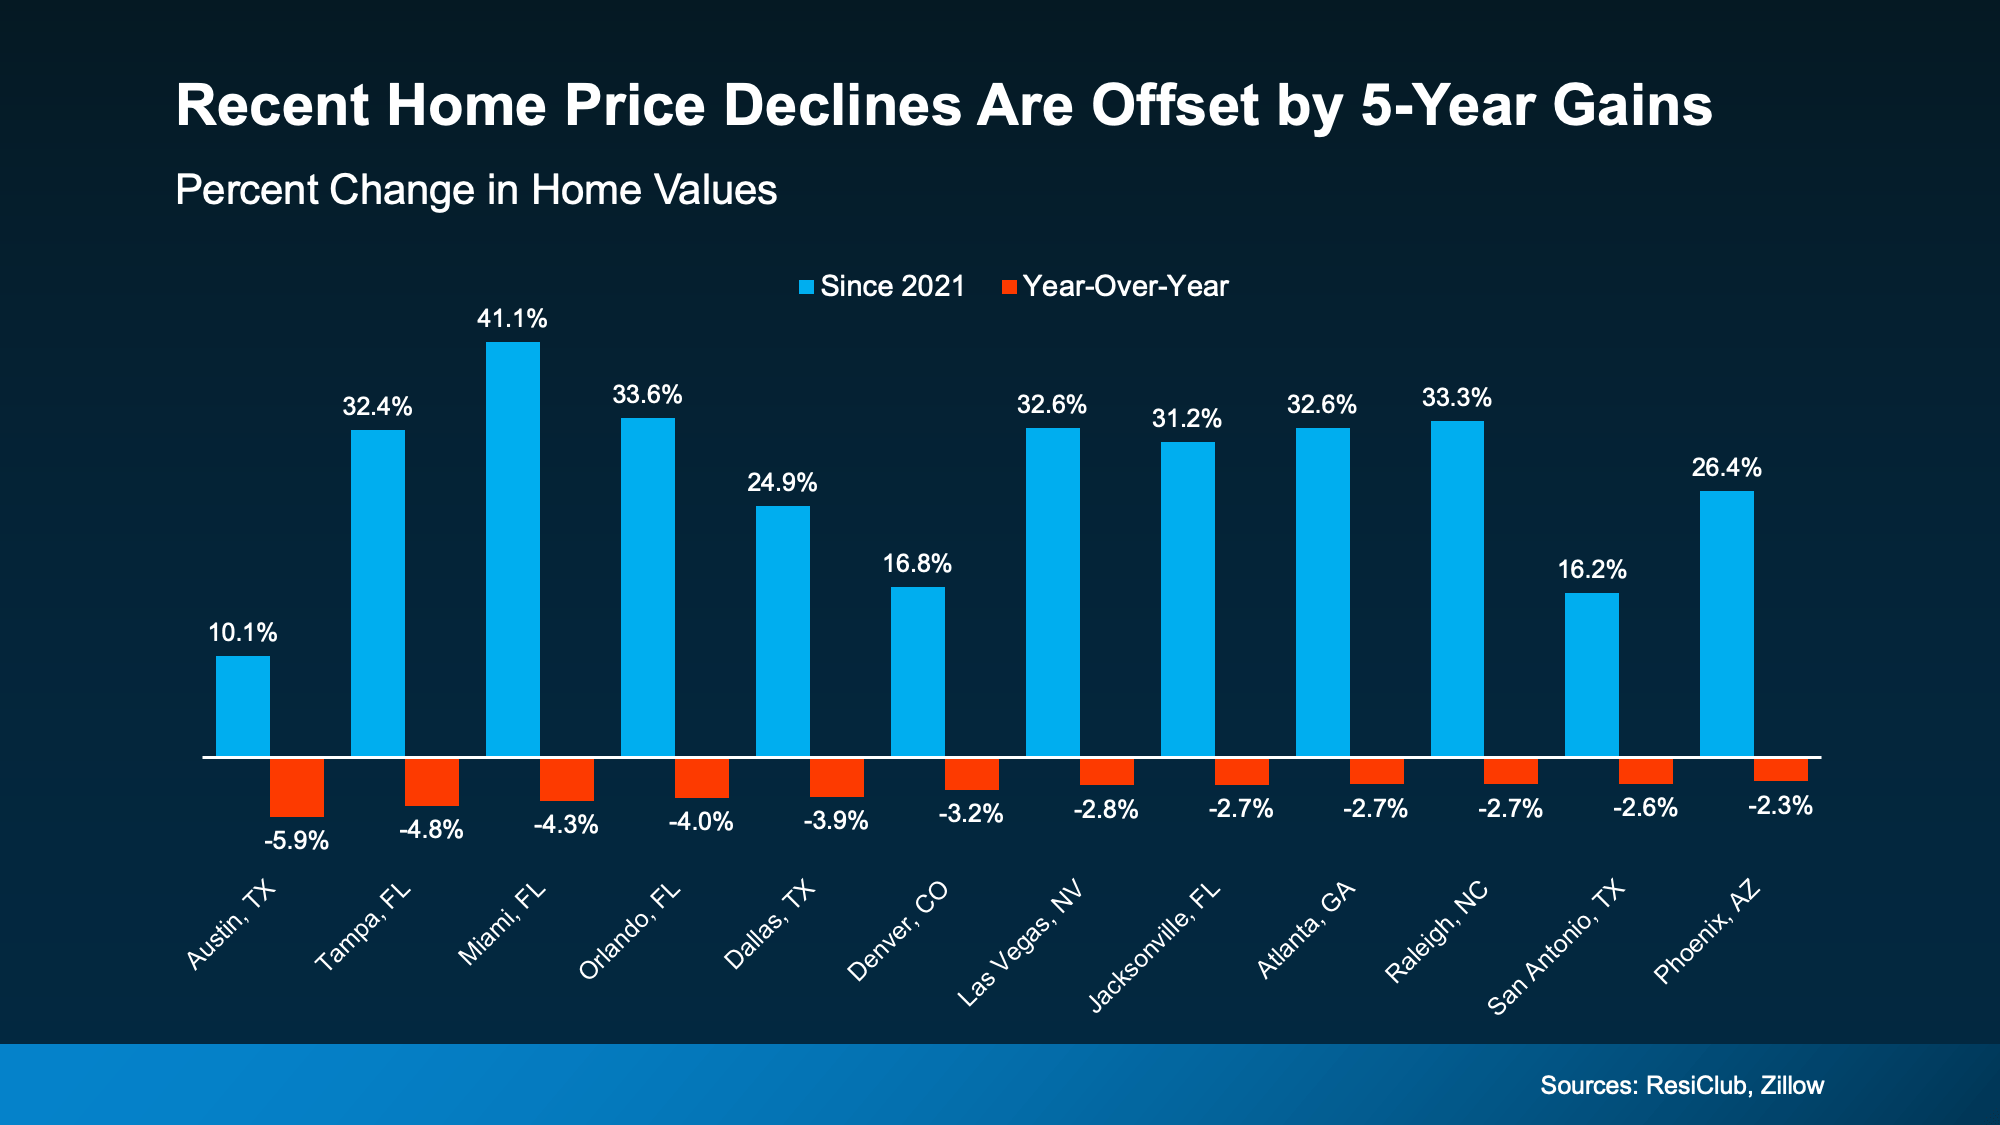
You’ve probably seen this one, too. The confusion is coming from the fact that some metros are experiencing slight price declines. And influencers are running with that and saying prices are crashing. But that’s not the reality.

Most areas are seeing prices rise, not fall. And that’s because:

  • Many homeowners aren’t selling because they don’t want to give up the low mortgage rate they locked in a few years ago. And that’s keeping a lid on how much inventory can grow.
  • Since inventory is still below pre-pandemic norms, there aren’t enough homes for sale to cause a price crash.
  • And even in markets with more inventory, some sellers are choosing to pull their homes off the market instead of cutting prices.

And those are 3 big reasons prices aren’t headed for a crash. 

And even in the markets experiencing mild declines, the drops aren’t enough to cancel out the big gains most homeowners have seen in the last 5 years (see graph below):

That’s not a crash. That’s just prices moderating after a few record-breaking years.
Bottom Line

Online posts are going to make things sound worse than they are. If you want a true, data-bound look at what’s really happening in today’s market, lean on a real estate agent.

Connect with a local agent so you have someone to separate fact from fiction today.

More Options Are Popping Up This Spring

More Options Are Popping Up This Spring Simplifying The Market

Did you try to buy a home last year, but you ended up pressing pause?

Maybe you couldn’t find a home that really fit your needs. Or maybe the ones you liked just weren’t affordable. According to a recent survey from NerdWallet, those were the top two reasons buyers gave up on their search in 2025.

But this Spring, there’s one trend that could help fix both of those frustration points: more homes are hitting the market.

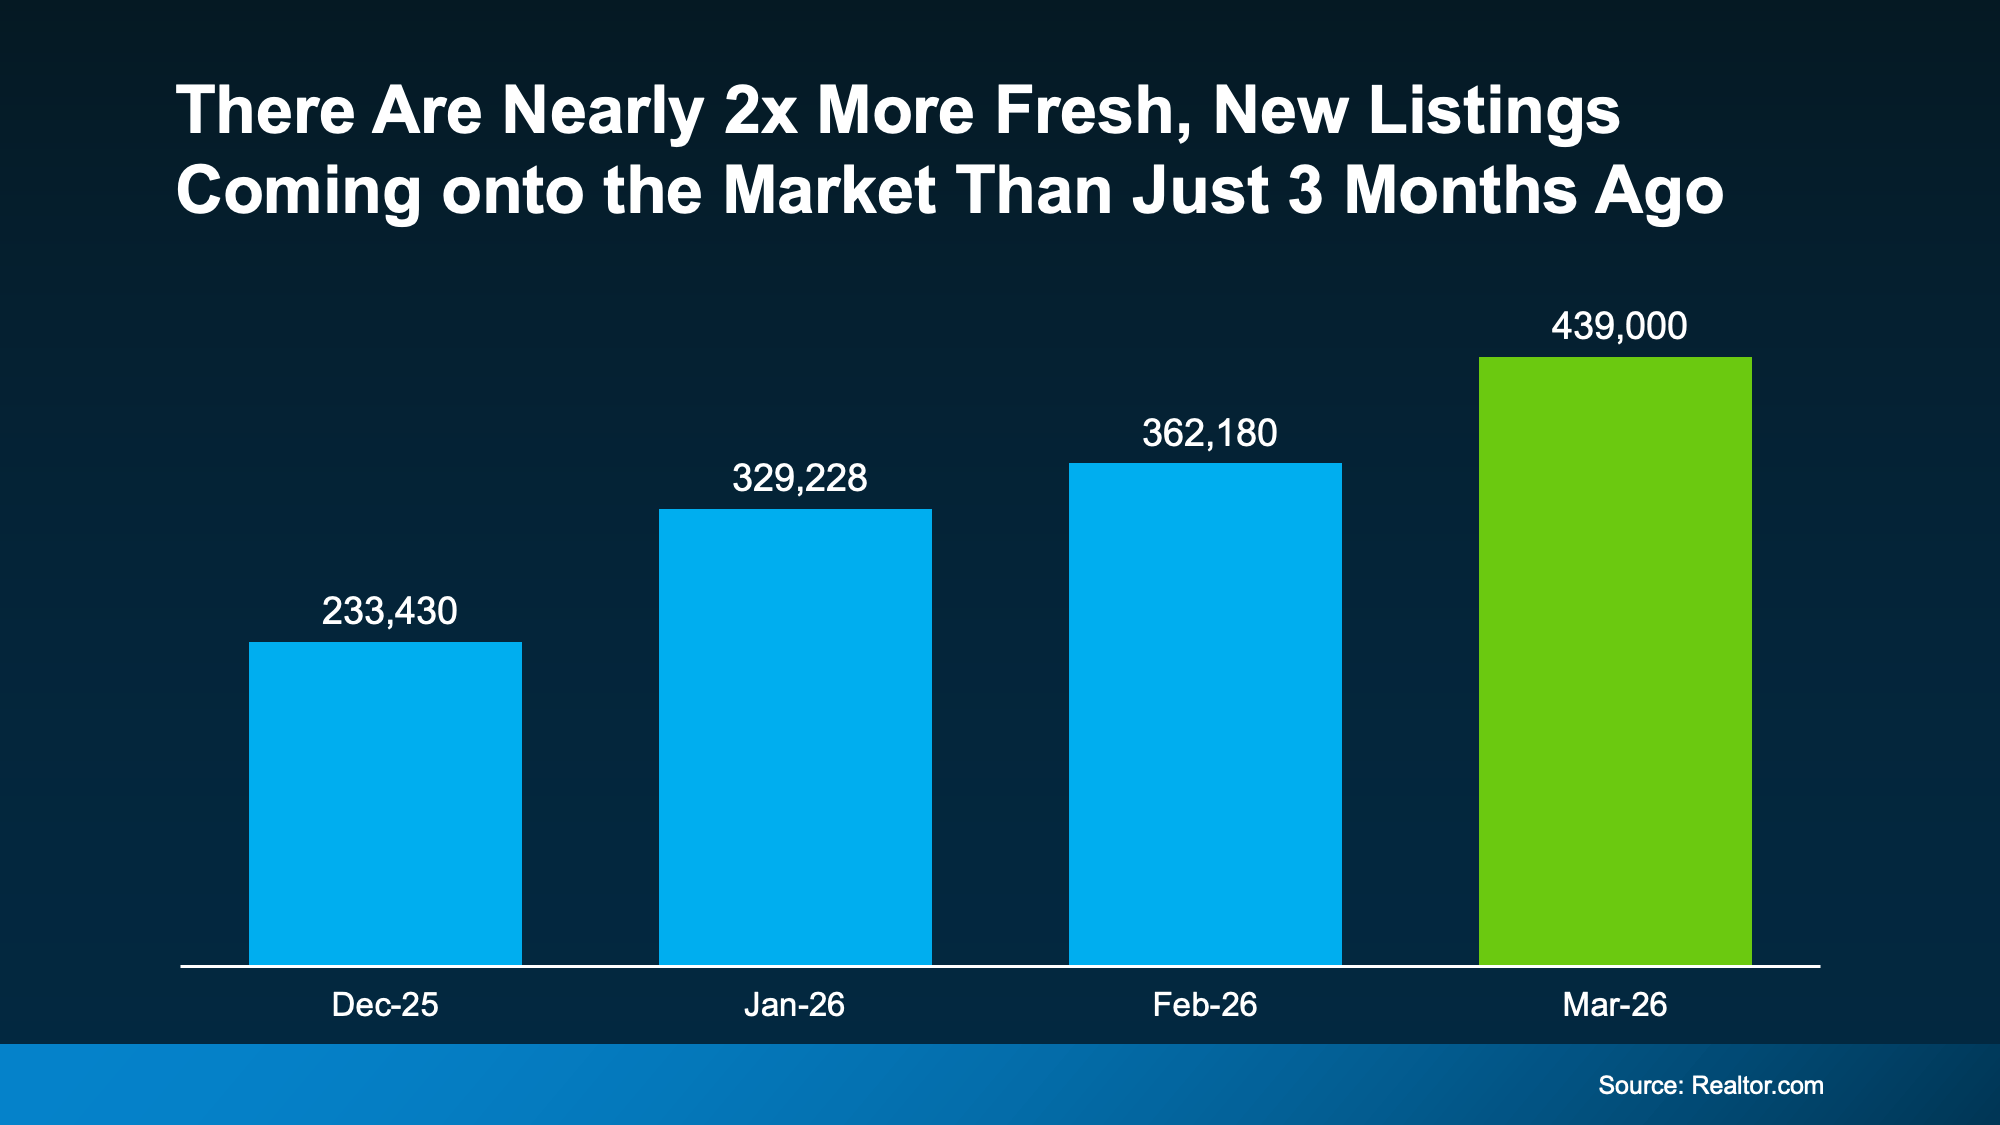
The Number of Fresh Listings Is Almost 2x Higher Than a Few Months Ago

Data from Realtor.com shows there are nearly 2x as many new listings hitting the market today as there were just 3 months ago. Those are homes the seller just put up for sale (see graph below):

a graph of a bar chartThat’s a significant rise. And while we usually see an uptick as we head into the busiest time of the year, this increase was bigger than normal. Jake Krimmel, Senior Economist at Realtor.com, explains:

New listings jumped 21.2% from February to 439,000, a larger-than-typical seasonal surge . . . March typically sees the biggest month-over-month jump in new listings of the entire buying season, averaging an 18% increase since 2017; this year it exceeded 20%.”

That means more sellers are jumping back into the market, and that’s giving buyers more fresh options to choose from. So, if you’d felt like you’d seen everything out there and still nothing was quite right, this may be your moment.

With that many “just listed” homes, one of them could be exactly what you’ve been searching for.

Where You Have More Options

And this trend is happening across most of the country, so you should have more options pretty much whereever you are.

Earlier this year, the Northeast had fewer new listings because winter storms delayed sellers from putting their homes on the market. But now, that region is catching up fast.

In March, new listings jumped across nearly every state, especially in the Northeast, helping drive a strong national rebound.

What Rising Inventory Means for You

Right now, there are almost a million homes for sale nationwide. That’s up over 8% compared to last year.

With that many homes on the market, there’s a much better chance something will fit what you’re looking for, especially with so many fresh options being added right now. As Odeta Kushi, Deputy Chief Economist at First American, explains:

“One of the most encouraging signals heading into the spring home-buying season is the improvement in for-sale inventory levels compared with last year. . . More homes on the market give buyers greater choice and, combined with improved buying power, expand the range of homes they can realistically consider.

In other words, your search may feel very different this year.

Bottom Line

More fresh listings are hitting the market right now, and that’s creating real opportunity.

If you put your search on hold last year, this Spring may be the time to jump back in. Connect with a local real estate agent to see what’s newly available in your area.

Rent or Buy? The Real Tradeoff Most People Don’t Talk About

Rent or Buy? The Real Tradeoff Most People Don’t Talk About Simplifying The Market

You’ve probably asked yourself lately: Is it even worth trying to buy a home right now? It’s a question a lot of people are asking.

With today’s home prices and mortgage rates, renting can feel like the easier path. In some cases, it might even seem like the only realistic option right now. And if that’s where you are, there’s nothing wrong with that.

But if you’re weighing the decision, there’s one part of the conversation that doesn’t get talked about enough.

It’s what each choice does for your future.

What Renting Really Gets You (And What It Doesn’t)

Depending on your situation, renting does have some advantages:

  • Lower upfront costs.
  • Less responsibility.
  • More flexibility to move when you want.

But even with those benefits, a Bank of America survey found 70% of aspiring homeowners worry about what long-term renting means for their future. And that concern comes down to one thing: you’re not building anything for your future. As Yahoo Finance explains:

“Paying rent doesn’t build equity. You get a place to live, but no ownership stake, no price appreciation, and no asset to leverage for future borrowing or investment.”

So, while renting may feel easier, the flexibility you get comes at a cost.

How Homeownership Builds Your Wealth Over Time

On the other hand, owning a home is one of the most consistent ways people build wealth over time. Why? When you’re a homeowner, you gain something called equity. That’s the difference between what your home is worth and what you owe.

That equity grows with every monthly payment you make. It also gets a boost as home values go up through the years – and it adds up quicker than you may think.

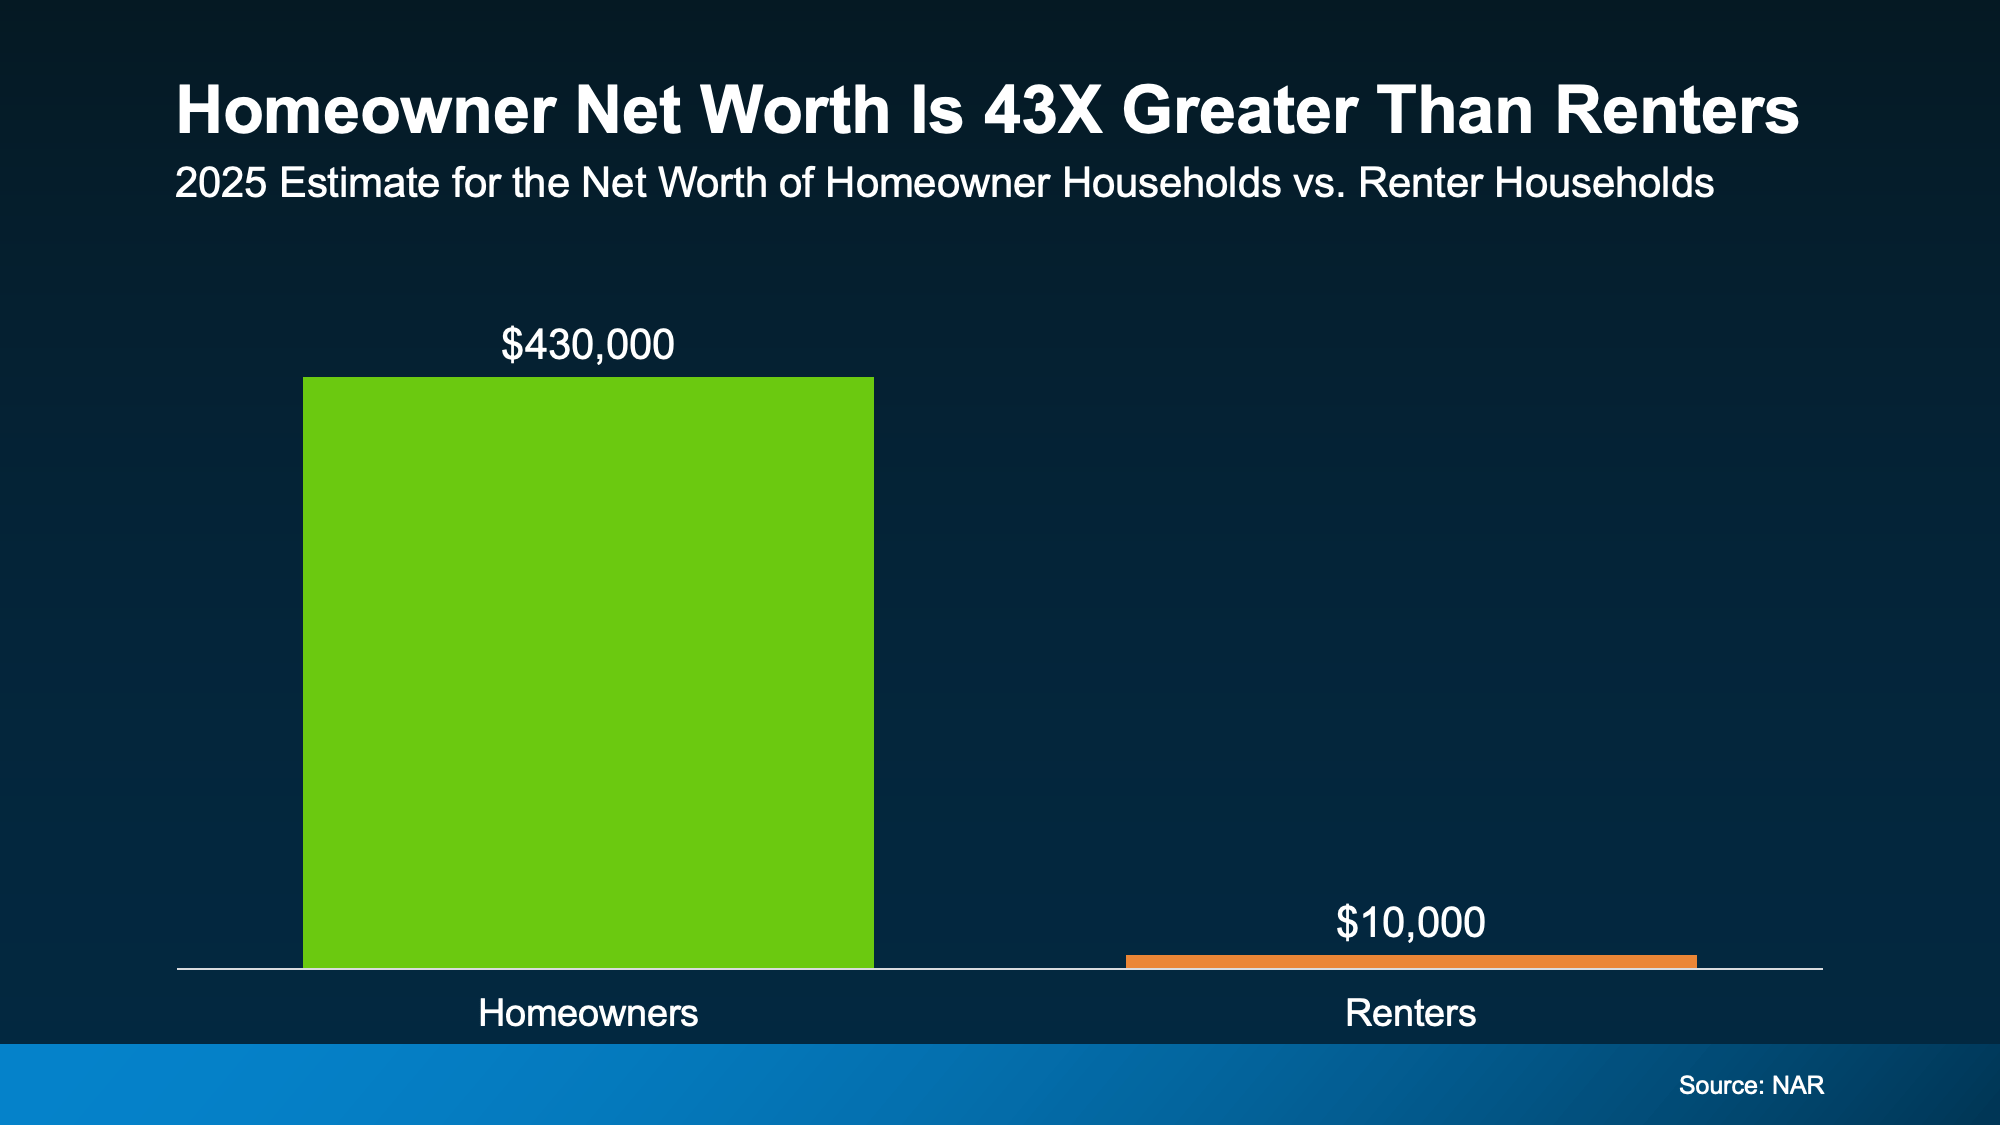
Today, the National Association of Realtors (NAR) says the average homeowner’s net worth is 43X greater than that of a renter:

a graph of a number of peopleThe dollars in the visual don’t lie. On average, here’s how net worth compares:

  • Homeowners: $430k
  • Renters: $10k

And it’s not because homeowners make wildly different decisions day to day. It’s because over time, one path builds something, and the other doesn’t.

So sure, buying comes with some upfront costs and more responsibility. But it’s basically a savings account you can live in.

The Gap Is Growing Over Time

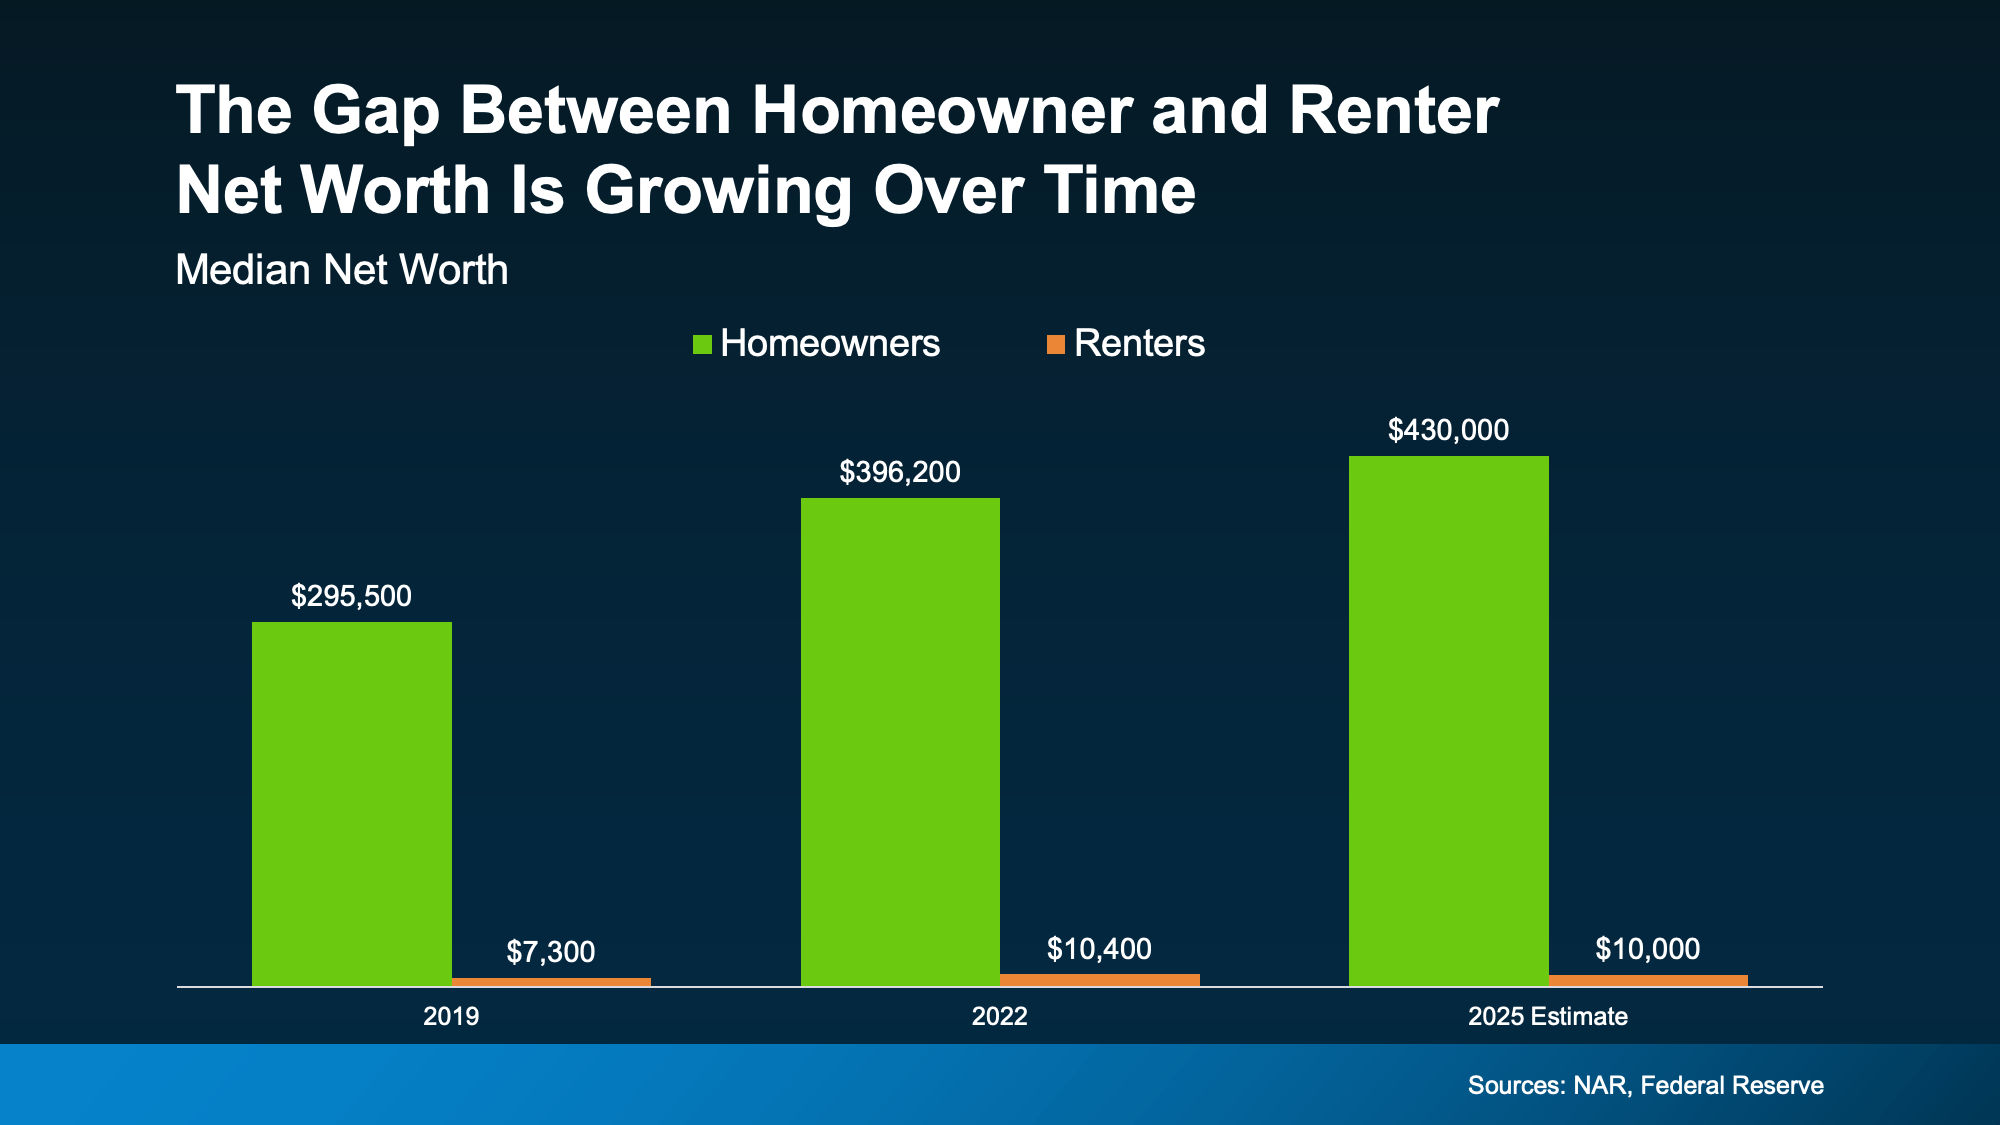
And here’s something else interesting. That net worth gap between renters and homeowners has been widening over time, not shrinking.

If you look back at the reports on net worth through the years, you can see the gap is growing as homeowners gain wealth and renters stay stuck in the rental trap (see graph below):

a graph of green and blue barsEven in 2025, when home prices were moderating, homeowners still gained even more ground. And that tells you something important:

When you can afford it and you’re ready for the responsibility, history shows buying is usually worth it in the long run. Because either way, you’re paying for someone’s mortgage and building someone’s net worth.

When you rent, it’s your landlord’s mortgage – not yours. But when you buy? Your monthly payments help build equity.

The question is: whose do you want to pay? Yours or theirs?

So, Should You Buy a Home Now?

The short answer is, it depends on your situation.

While the long-term benefits of buying are clear, that doesn’t mean the timing is right for everyone right now. And that’s okay. You should only buy a home once you’re ready and the numbers work for you.

But whether you’re looking to buy now or planning for the future, the first step is the same. You should have a quick conversation with a local real estate agent about your goals, timeline, and budget.

They can help you run the numbers and see what’s realistic. You may find buying is closer than you thought. And if not, you’ll at least know exactly what it will take to get there.

Because the sooner you have a plan, the sooner you can decide when it makes sense, instead of wondering if it ever will.

Bottom Line

Renting may feel more do-able today. But over time, it could cost you.

If you want to ditch renting and start building something for your future, it starts with a simple conversation. Connect with a real estate agent to talk about your specific goals, and explore your options – so you’re ready when the time is right for you.